DOI:https://doi-0004.org/6812/17880166255901
SAIDI Mohammed 1, BEN SEGHIER Fatima Zohra 2, AZZAOUI Saadia 3, BOUAMRA Hacene 4, BOUAMRA Ahmed 5, BOUCHENTOUF Moulay Mostapha 6
1Lecturer Professor A. Oran Gradute School of Economics, Algeria, E-mail: mohammed.saidi@ese-oran.dz
2University of Larbi Tebessi – Tebessa, Laboratory of Economic Diversification Strategies for Achieving Food, Health, and Energy Security in Algeria, Algeria, E-mail: fatima.benseghier@univ-tebessa.dz
3Ahmed Draia University – Adrar, Laboratory of Algero-African Economic Integration, Algeria, E-mail: azza.saadia@univ-adrar.edu.dz
4University of Tebessa, Algeria, E-mail: hacene.bouamra@univ-tebessa.dz
5Abbas Laghrour University – Khenchela, Laboratory of Business Incubators and Local Development, Algeria, E-mail: bouamra.ahmed@univ-khenchela.dz
6University of Tamanrasset, Investment and Sustainable Development in Border Regions Laboratory, Algeria, E-mail: bouchentouf.moustapha@univ-tam.dz
Received: 17/06/2026 ; Published: 29/08/2026
Abstract:
This study investigates the non-linear, distribution-dependent transmission channels within the United States energy-macroeconomy nexus using high-frequency monthly data from February 1997 to February 2025. Utilizing a dual-system Quantile Autoregressive Distributed Lag (QARDL) approach, we analyze the asymmetric impacts of clean energy integration—differentiating between Variable Renewable Energy (VRE) and baseload nuclear power—on Wholesale Electricity Prices (Model 1) and Industrial Growth (Model 2), while controlling for natural gas market dynamics. The empirical results reveal severe structural asymmetries across conditional quantiles
In the power market, renewable energy exhibits a massive “peak-shaving” merit-order effect at the upper quantile , aggressively suppressing extreme wholesale price surges, while marginally increasing baseline costs at lower quantiles due to grid integration expenses. Crucially, the error correction mechanism indicates a breakdown of the market’s self-correcting capacity
during acute price volatility regimes. In the macroeconomic sphere, the “Green Growth” hypothesis is robustly validated, as renewable energy consistently and positively stimulates industrial production across all business cycle phases. Conversely, nuclear generation acts as a vital structural anchor specifically during peak economic expansions
, highlighting the indispensability of uninterruptible baseload power. These findings underscore that one-size-fits-all energy policies are inadequate; regulators must adopt state-dependent interventions, reform marginal pricing frameworks, and secure baseload asset longevity to sustain resilient economic decarbonization.
Keywords: Quantile ARDL (QARDL); Clean Energy Transition; Wholesale Electricity Prices; Industrial Growth; Merit-Order Effect; Asymmetric Cointegration.
JEL Classification: Q42; Q43; Q48; C22; L94.
Introduction
Over the past three decades, the structural architecture of the United States power sector has undergone a profound paradigm shift. Driven by wholesale market deregulation, stringent carbon-mitigation mandates, and rapid technological advancements, the generation mix has transitioned away from traditional fossil-fuel dominance toward an increasingly diversified matrix. Within this dynamic landscape, the systemic interplay between Variable Renewable Energy (VRE) sources (e.g., wind and solar) and stable baseload generation (e.g., nuclear power) has emerged as a cornerstone for both electricity market stability and macroeconomic performance.
However, this transition introduces complex market dynamics. The intermittent and non-dispatchable nature of renewable energy, combined with the extreme price volatility of primary fossil fuels like natural gas ($NG$), has injected severe non-linearities into wholesale power markets. These frictions frequently manifest as abrupt electricity price spikes or periods of localized negative pricing. Far from being confined to utility balance sheets, these power market shocks propagate asymmetrically across the real economy. The industrial sector, which hinges critically on uninterrupted, cost-effective energy inputs, exhibits varying sensitivities to these variations depending on the broader macroeconomic state—ranging from recessionary troughs to expansionary peaks.
Despite the volume of literature examining the energy-growth nexus, a critical empirical gap persists. Traditional econometric frameworks—such as standard Autoregressive Distributed Lag (ARDL) models or linear cointegration techniques—operate under the restrictive assumption of parameter constancy. They implicitly assume that energy shocks exert a symmetric, uniform impact across all time horizons and market regimes. This structural assumption fails to capture distribution-dependent behaviors. It overlooks how the marginal impact of renewable or nuclear generation on wholesale prices changes when the market is in a state of extreme stress (upper quantiles) compared to baseline operations. Similarly, linear models obscure how industrial growth ($IG$) absorbs energy price shocks during a prolonged economic slowdown versus a booming expansionary phase.
To bridge this empirical gap, this study implements a dual-system framework utilizing the Quantile Autoregressive Distributed Lag (QARDL) methodology developed by Cho et al. (2015). This advanced framework relaxes the assumption of linearity, permitting the decomposition of long-run and short-run dynamics across a continuous spectrum of conditional quantiles ($\tau$). By analyzing high-frequency monthly data stretching from February 1997 to February 2025, this paper investigates the non-linear trajectories of the US energy-macroeconomy nexus through two interconnected empirical streams: Model 1 evaluates the asymmetric determinants of Wholesale Electricity Prices ($EP$), while Model 2 assesses the distribution-dependent responses of Industrial Growth ($IG$).
Consequent to this design, this study offers three primary contributions to the existing literature:
- A Dual Systemic Framework: Unlike single-equation studies, this paper maps the entire transmission channel by simultaneously modeling wholesale price variations and macroeconomic industrial output, offering a holistic view of the power-industrial nexus.
- Empirical Validation of the Merit-Order Effect: It provides rigorous empirical evidence regarding the “peak-shaving” capacity of renewable energy, demonstrating how zero-marginal-cost generation suppresses extreme wholesale price spikes at the upper quantiles, while quantifying integration costs at lower quantiles.
- Granular Testing of the Green Growth Hypothesis: It decouples the long-run and short-run structural impacts of clean energy on industrial output across the business cycle, highlighting the vital role of nuclear infrastructure as a stabilizing baseline asset during peak industrial demand regimes.
1. Theoretical Framework
1.1 The Energy-Growth Nexus and Production Function Dynamics
The theoretical architecture governing the relationship between energy consumption and macroeconomic performance is fundamentally rooted within the aggregate production function framework, which establishes long-run cointegrating vectors among energy inputs, capital stock, labor dynamics, and economic output. Historically, traditional paradigms in energy economics assumed a symmetric linkage, implying that positive and negative changes in energy consumption of equal magnitude would elicit uniform, identical impacts on economic growth. Contemporary economic theory challenges this linear assumption, demonstrating that variations in energy consumption do not automatically transmit with equal intensity across opposing directional movements. Consequently, an energy contraction may affect economic growth through entirely different structural mechanisms than an equivalent energy expansion (Tugcu & Topcu, 2018).
Empirical insights within this domain highlight that cointegrating properties, asymmetric behaviors, and causal directions remain highly sensitive to the specific production functions and energy proxies selected. When energy consumption is quantified strictly through total energy utilization, strong theoretical support emerges for a non-linear, long-run asymmetric relationship between energy consumption and economic growth (Tugcu & Topcu, 2018). Conversely, alternative frameworks demonstrate that while allowing high-frequency energy data to integrate into a low-frequency economic growth framework—such as through the Autoregressive Distributed Lag-Mixed Data Sampling (ADL-MIDAS) approach—significantly optimizes both in-sample and out-of-sample forecasting accuracy, accounting for directional asymmetries does not yield statistically significant differences within certain aggregate settings. This variance underscores that energy exhibits significant predictive capacity for growth regardless of the underlying measures used, rendering context-specific analysis essential. Ultimately, these shifting dynamics demonstrate that a balanced, sustainable energy portfolio is a core requirement for continuous economic progress, and this portfolio must collectively possess the structural capability to provide reliable, resilient electricity at stable, affordable prices (Setshedi & Mah, 2025).
1.2 Asymmetric Transmission Channels of Nuclear Energy Shocks
Nuclear energy possesses highly specific technical and economic attributes that induce distinct asymmetric transmission channels within environmental and electricity market states. Structurally, nuclear power represents a core contributor to the clean energy supply, operating not only as a primary non-carbon generation source but also as a baseline power asset that complements and enables the stable integration of highly variable clean energy alternatives (Bragg‐Sitton et al., 2020). Within the United States context, nuclear power occupies a central position, currently supplying more than half of the nationwide non-emitting electricity generation portfolio and accounting for 19% of aggregate U.S. electricity production (Bragg‐Sitton et al., 2020; Uribe et al., 2023). This extensive baseline capacity underpins growing cross-partisan policy support in both the United States and Canada, driven by the technology’s capacity to simultaneously resolve air quality and climate goals through non-carbon electricity while preserving grid reliability via baseload supply stability (Rabe, 2025). Nuclear power is thus considered indispensable for achieving statutory decarbonization goals, which include a 50% reduction in carbon emissions by the end of the decade, a 100% clean electricity grid by 2035, and a net-zero emissions economy by 2050 (Uribe et al., 2023).
The transmission of shocks within the nuclear energy sector operates through clear directional asymmetries across different economic and environmental states. On the environmental dimension, while structural economic growth and trade openness systematically harm environmental sustainability, positive supply-side shocks to nuclear capacity significantly improve environmental quality (Caglar et al., 2024). However, negative nuclear shocks deteriorate environmental sustainability within the United States, a directional divergence that does not uniformly occur in other advanced nuclear states like France, thereby highlighting market-specific programmatic vulnerabilities (Caglar et al., 2024). In South Asian economies, nuclear energy similarly exhibits large asymmetric effects, where positive increases in nuclear energy scale down emissions, but negative shocks or disruptions trigger immediate emission spikes, demonstrating that expansions yield beneficial results while generation contractions carry disproportionate environmental costs (Bhatti & Shafiq, 2025).
On the pricing and supply dimension, nuclear assets traditionally provide inflexible, high-capacity baseload power to the grid (Worsham et al., 2023). Because of this configuration, structural generation disruptions act as sharp supply-side shocks that directly distort market-clearing equilibrium positions in interconnected wholesale electricity markets. In the short run, the retirement of a single 1000 MW nuclear facility causes significant price escalation, raising wholesale electricity costs by approximately 9% in the Independent System Operator of New England market and by 7% in the New York Independent System Operator market at their respective reference hubs, while generating immediate upward price spillovers in adjacent interconnected power markets (Zarnikau et al., 2025).
The long-term economic feasibility of expanding nuclear assets, particularly through structural advancements in creating smaller, safer Small Modular Reactors (SMRs), depends heavily on prevailing market price scenarios and policy support mechanism designs, including the Inflation Reduction Act (IRA) tax credits. In low-price market environments, such as the ERCOT market scenario, SMR deployments are economically feasible only if capital expenditures and variable operations and maintenance (O&M) costs remain minimal (Larsen et al., 2024). Conversely, the presence of an extended Production Tax Credit (PTC) duration combined with higher-price market environments, such as New England, structurally broadens the commercial feasibility of nuclear reactor advancements (Larsen et al., 2024). Beyond traditional power generation, advanced nuclear units possess significant utility coupling potentials with industrial applications, providing low-carbon energy for process heating, hydrogen generation, and on-site industrial electricity demand, which extends the value proposition of nuclear assets beyond simple electricity generation (Worsham et al., 2023). The implementation of integrated multi-input, multi-output energy systems via programs like the Integrated Energy Systems (IES)—formerly the Nuclear-Renewable Hybrid Energy Systems (N-R HES) program—allows nuclear energy to complement variable renewables while using excess thermal and electrical energy to support the production of nonelectric commodities, including potable water, hydrogen, and liquid fuels (Bragg‐Sitton et al., 2020).
1.3 Renewable Supply Shocks and the Merit-Order Price Mechanism
The structural integration of renewable energy sources systematically reshapes wholesale electricity price formation through the operational mechanics of the merit-order effect. Within wholesale electricity dispatch frameworks, renewable energy producers possess the capacity to submit selling bids characterized by near-zero marginal costs, given that their power generation faces no direct fuel costs associated with the utilization of wind or solar resources (Fernández et al., 2020). Consequently, when a regional market operator integrates these low-marginal-cost renewable bids into the merit-order generation curve, conventional generation technologies—which carry high marginal costs driven by fossil fuel obligations—are displaced horizontally to the right (Fernández et al., 2020). This rightward displacement of the conventional merit-order curve yields a lower market clearing price, generates a marginal increment in the total volume of traded energy due to an almost inelastic short-run demand curve, and minimizes the aggregate cost of energy traded across the wholesale market (Fernández et al., 2020).
These pricing dynamics exhibit substantial cross-market spillovers and geographic transmission channels due to the highly interconnected nature of modern power systems. Localized energy policies promoting renewable energy development, alongside Canadian hydroelectric imports, trigger short-run reductions in average wholesale prices across the entire Northeast United States, meaning that supply shifts in one regional market directly impact wholesale pricing structures in adjacent interconnected networks. Similarly, proposed large-scale offshore wind farms are projected to lower wholesale clearing prices both at local reference hubs and within neighboring power markets (Zarnikau et al., 2025).
The long-term temporal dynamics of the merit-order effect present unique structural challenges. The reduction in average wholesale electricity prices driven by expanded renewable capacity frequently raises concerns regarding the long-term economic viability of legacy conventional power plants (Antweiler & Muesgens, 2021). Theoretical and empirical evaluations clarify that the merit-order effect operates primarily as a temporary phenomenon caused by the slow pace of structural capacity adjustments within power systems. Over longer horizons, the introduction of variable renewables exerts only a mild long-term beneficial effect because renewables compete with monopolistic baseload power providers to a limited extent, rendering long-term concerns regarding the structural collapse of conventional legacy assets only partially justified (Antweiler & Muesgens, 2021).
Furthermore, renewable energy supply shocks introduce distinct variations across the conditional distribution of electricity prices. While wind and solar generation exert a uniform negative impact on the absolute median price level, their impacts on price volatility—measured via the inter-quantile range (IQR)—are highly heterogeneous and conditional upon total demand levels. Wind generation expands price volatility when aggregate demand is low but compresses volatility when demand is high, whereas solar power capacity stabilizes price variance under moderate demand conditions. This structural divergence necessitates balanced renewable asset deployment policies to optimize grid stability (Maciejowska, 2020). Additionally, matching expanding industrial electrification demand with variable wind capacity can restore wholesale prices to baseline levels but reintroduces market power dynamics, as flexible assets like hydroelectric facilities exploit variable renewable energy (VRE) intermittency and industrial load profiles to maximize their strategic market payoffs (Roberts et al., 2025). Finally, environmental responses to renewable energy shocks display directional non-linearities: both positive and negative shocks in renewable energy consumption operate to mitigate environmental degradation, implying that downward fluctuations in renewable resource usage do not automatically deteriorate environmental conditions in a symmetric, proportional manner (Abdul-Mumuni et al., 2022; Wani et al., 2024).
1.4 Sectoral Demand Elasticities and Industrial Growth Linkages
The macroeconomic transmission of pricing shocks from electricity markets into the real economy is directly mediated by sectoral electricity demand elasticities and the structural cointegrating linkages binding power consumption to manufacturing outputs. The long-run responsive behaviors of economic actors to pricing shifts vary dramatically across residential, commercial, and industrial segments. State-level panel data within the Northeastern United States demonstrates that the long-run income elasticity of electricity demand is exceptionally high within the industrial sector, reaching a coefficient of 1.95, compared to the less elastic residential (0.93) and commercial (0.53) sectors. This high baseline income elasticity underscores that industrial output and production expansions generate intensive demand surges for grid power (Gautam & Paudel, 2018). Conversely, while residential electricity demand remains responsive to its own price over long horizons, showing an own-price elasticity of -0.11, and entirely irresponsive in the short run, industrial performance is dictated by the continuous availability of affordable, stable power (Gautam & Paudel, 2018). Price volatility or escalating electricity costs operate as an explicit constraint on manufacturing performance, creating a negative feedback loop where high electricity prices depress industrial electricity consumption, and contracting industrial output further minimizes sectoral power utilization (Setshedi & Mah, 2025).
In terms of aggregate development, power consumption is positively and significantly related to manufacturing sector output, establishing that structural improvements within the power sector directly stimulate manufacturing growth (Nwosu et al., 2024). This relationship exhibits a powerful error correction mechanism, wherein short-run deviations from the long-run equilibrium state are corrected at an annual rate of up to 83%, demonstrating rapid adjustment behaviors toward structural stability (Nwosu et al., 2024). While manufacturing output benefits from consistent electricity availability across both short- and long-run horizons, this positive output transmission requires prolonged periods to manifest, becoming highly statistically significant only over time (Gold et al., 2024). On a broader scale, cross-country evidence reinforces that consistent electricity production generates positive, driving impacts on both industrial production index levels and sustainable economic growth pathways (Yu et al., 2019). Consequently, maintaining industrial competitiveness requires targeted public policies designed to encourage infrastructure investors through tax advantages, strategic location orientation, financial mechanisms, and intensive investments in renewable energy and smart grid integration (Setshedi & Mah, 2025; Yu et al., 2019).
2. Empirical Literature Review
The empirical literature surrounding energy system integration, electricity pricing mechanisms, and macroeconomic growth can be categorized into two primary thematic bodies: studies evaluating the energy-growth nexus, and investigations focusing on the energy-pricing-industrial output nexus. These bodies are further differentiated by their reliance on traditional symmetric frameworks versus advanced non-linear methodologies.
Empirical evaluations of the energy-growth nexus across diverse geographic and economic contexts reveal substantial structural heterogeneity. Cross-country panel evidence from Sub-Saharan African economies obtained from PMG-ARDL and QARDL estimators shows that both fossil fuel energy and renewable energy consumption exert statistically significant positive effects on long-run economic growth. Crucially, within these developing settings, the macroeconomic magnitude of renewable energy consumption outpaces that of traditional fossil fuels, driven by transmission channels where renewable energy lowers the marginal cost of electricity, facilitates green industrial transformation, and acts as a baseline catalyst for technological innovation (Türüç-Seraj & Üçışık-Erbilen, 2025). In contrast, country-specific historical evidence from Nigeria indicates that despite absolute descriptive increases in both variables between 1990 and 2016, renewable energy consumption failed to assert a statistically significant positive impact on economic growth (Azeakpono & Lloyd, 2020). Within advanced economic frameworks like the United States, long-run economic growth is significantly driven by shale gas development and capital stock accumulation, whereas labor force inputs demonstrate a positive but statistically insignificant role in driving output (Solarin & Bello, 2020).
From an environmental standpoint, aggregate multi-country evaluations across the G20 emphasize complex causal pathways, establishing unidirectional Granger causality running from economic growth to Industry 4.0 adoption, research and development (R&D) expenditures, and renewable energy output, alongside unidirectional pathways running from industrial structure, trade openness, and financial development to renewable output (Bildirici et al., 2023). This is complemented by bidirectional feedback loops between renewable energy expansion and Industry 4.0 infrastructure, which highlights the renewable-enhancing effects of Industry 4.0 (Bildirici et al., 2023). When environmental states are evaluated in conjunction with growth parameters, Method of Moments Quantile Regression (MMQR) models reveal that GDP expansion increases carbon emissions across all conditional quantiles, while renewable energy consumption and institutional quality exert significant negative impacts, mitigating environmental degradation (Almulhim et al., 2025).
The empirical literature evaluating regional power grid dynamics demonstrates highly localized structural interactions. Within the US PJM Interconnection, empirical assessments show that the expansion of natural gas-fired electricity generation assets does not crowd out the deployment of installed distributed solar PV systems within capacity markets (Nyangon & Byrne, 2022). However, intensive heterogeneity persists, as distributed solar development reveals no statistical relationship with nuclear, coal, hydroelectric generation, or aggregate electricity consumption levels (Nyangon & Byrne, 2022). Regarding industrial electrification and demand-side shocks, evidence from advanced power systems indicates that expanded industrial electricity demand diminishes the market power of generation firms but increases average market prices, a dynamic that can be neutralized by aligning industrial load profiles with onshore wind capacity (Roberts et al., 2025). On a broader international scale, empirical evidence from the BRICS bloc indicates that electricity production yields a uniform, positive effect on both industrial production indexes and sustainable economic growth, justifying the deployment of targeted investor incentives through tax advantages, location orientation, and financing mechanisms (Yu et al., 2019).
The historical baseline of empirical energy economics rests heavily upon linear models that assume symmetric cointegrating properties, which frequently leads to highly volatile and inconclusive causality findings across varying production functions and energy proxies (Tugcu & Topcu, 2018). To capture real-world non-linearities, empirical studies have increasingly turned to Nonlinear Autoregressive Distributed Lag (NARDL) frameworks. In Pakistan, NARDL estimations confirm that positive and negative changes in renewable energy consumption and external shocks possess a significant long-run asymmetric relationship with economic growth, while non-renewable energy consumption exerts a negative and significant impact on output (Abbasi et al., 2020). NARDL applications evaluating technological shifts in China indicate that positive developments in artificial intelligence (AI) accelerate decarbonization, while negative AI shocks linked to energy-intensive computing infrastructures temporarily expand greenhouse gas emissions before stabilizing (Huang et al., 2025). Similarly, NARDL analysis in Iran confirms that positive and negative shocks of GDP and economic policy uncertainty significantly impact carbon emissions, validating an asymmetric production-emission link, whereas the uncertainty index displays a symmetric relationship where a shock in the index lowers carbon emissions (Ashena & Shahpari, 2021).
The Quantile Autoregressive Distributed Lag (QARDL) framework, originally developed by Cho et al. (2015), represents a major methodological advancement within empirical energy economics. Traditional linear ARDL and mean-based asymmetric NARDL models are restricted by their reliance on conditional mean estimations, which assume parameter homogeneity and collapse all empirical estimates into a single average tracking indicator. This technical limitation frequently conceals critical threshold effects, non-linearities, and structural shifts that occur across different states of the dependent variable. The QARDL framework resolves this constraint by integrating the directional flexibility of error-correction modeling with the distribution-dependent analytical power of quantile regression (Cho et al., 2015). This allows researchers to estimate long-run cointegrating vectors and short-run error correction dynamics across the entire conditional distribution of the dependent variable (\tau), uncovering how the relationships between energy variables change during periods of market reorganization, price volatility, or economic contractions.
Empirical applications of the QARDL framework demonstrate its analytical precision across diverse macroeconomic and energy settings. Within the Pakistani context, QARDL estimations reveal that the long-run associations binding human development, energy production, and economic growth are strictly quantile-dependent, with short- and long-run relationships statistically validated across individual quantiles via Wald tests and Error Correction Models (Luqman et al., 2021). These models confirm that changes in human development and economic growth are responsible for past and current variations in energy production and corruption (Luqman et al., 2021). In China, QARDL modeling demonstrates that the positive impacts of information and communications technology (ICT) on economic growth and energy consumption remain stable and positive across all conditional quantiles in both the short and long run, a localized finding reinforced by Quantile Granger Causality tests confirming robust bidirectional feedback mechanisms (Wang et al., 2024).
Furthermore, QARDL applications in Nigeria expose the distributional nature of financial development, showing that its positive impact on CO₂ emissions and ecological footprints intensifies significantly at the middle and upper quantiles, confirming that financial shocks generate more severe environmental degradation during high-emission states (Ihezukwu et al., 2025). In the United States, QARDL frameworks applied to quarterly data from 2002Q1 to 2019Q1 establish that shale gas development and capital stock act as significant positive long-run drivers of economic growth, whereas labor force contributions remain positive but statistically insignificant across the distribution (Solarin & Bello, 2020). Finally, within electricity markets, QARDL applications in South Africa from 1975 to 2023 reveal that the negative transmission of high electricity prices and industrial output fluctuations on industrial electricity consumption varies substantially across conditional quantiles, demonstrating that industrial energy demand responses are fundamentally distribution-dependent (Setshedi & Mah, 2025).
Despite the insights provided by asymmetric and quantile modeling frameworks, a major research gap persists within the empirical literature. Existing energy economics studies either analyze wholesale pricing dynamics through the merit-order effect without incorporating macro-industrial output feedback loops, or evaluate the energy-growth nexus without considering distribution-dependent pricing volatility across electricity markets. Specifically, the literature has failed to jointly evaluate the quantile-dependent, non-linear, and asymmetric influences of concurrent nuclear and renewable energy integration on both the wholesale electricity pricing distribution and industrial growth parameters within a single, unified econometric framework. Consequently, traditional models fail to explain how clean energy supply shocks interact across different conditional states of electricity costs and manufacturing performance in the United States. This study addresses this gap by applying a unified QARDL framework to capture the asymmetric and distribution-dependent transmission channels of nuclear and renewable energy integration on both market pricing and industrial performance.
3. Empirical Methodology and Data Specification
3.1 Data Framework and QARDL Model Specification
To investigate the non-linear, distribution-dependent relationships linking clean energy integration, electricity markets, and macroeconomic output in the United States, this study utilizes monthly frequency data covering the period from February 1997 to February 2025 (to
), yielding
historical observations.
To capture both the short-run dynamics and long-run cointegrating vectors across different states of the variables, we employ the Quantile Autoregressive Distributed Lag (QARDL) approach developed by Cho et al. (2015). The traditional ARDL model assumes parameter constancy across the conditional distribution. In contrast, the QARDL framework permits the parameters to vary across conditional quantiles (\tau), making it highly effective for modeling extreme market events, such as price spikes or industrial shocks.
The generalized QARDL Error Correction Models (ECM) for the two main relationships—Wholesale Electricity Pricing (Model 1) and Industrial Growth (Model 2)—are formulated as follows:
Model 1: Wholesale Electricity Pricing Dynamics
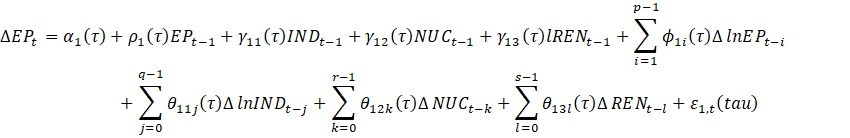
Model 2: Industrial Growth Dynamics
Where:
denotes the first-difference operator.
represents the conditional quantile, where
.
is the quantile-specific intercept.
and
capture the long-run structural parameters across quantiles.
and
capture the short-run dynamics and lag effects across quantiles.
represent the optimal lag lengths determined by standard information criteria.
is the stochastic error term evaluated at quantile
.
3.3 Descriptive Statistics and Correlation Analysis
To comprehend the foundational distributional properties and preliminary linear associations among the variables before executing the QARDL estimations, this section presents the descriptive statistics and the correlation matrix. The summary statistics, derived from 337 monthly observations, capture the central tendencies, dispersions, and boundaries of the dataset.
As detailed in Table 2, the Wholesale Electricity Price (EP) demonstrates significant volatility, with a mean of 191.18 and a wide range between 125.70 and 300.56, highlighting the pricing fluctuations inherent in deregulated power markets. Nuclear Power Generation (NUC) exhibits the largest absolute standard deviation (5724.50), reflecting major structural adjustments and capacity shifts over the decades. Industrial Growth (IG) maintains a mean of 96.00, anchoring the macroeconomic demand side. Furthermore, the newly introduced control variable, Natural Gas (NG), presents a mean of 4.11 and a standard deviation of 2.12, reflecting fuel market price dynamics.
Table 2: Descriptive statistics of the variables
| Variable | Observations | Mean | Std. Dev. | Minimum | Maximum |
| REN | 337 | 0.498 | 0.141 | 0.273 | 0.781 |
| NG | 337 | 4.112 | 2.121 | 1.490 | 13.420 |
| IG | 337 | 96.002 | 5.918 | 77.656 | 104.100 |
| EP | 337 | 191.181 | 46.501 | 125.700 | 300.563 |
| NUC | 337 | 64747.280 | 5724.502 | 44883.000 | 74649.000 |
Source: Authors’ calculations using Stata 18.
Table 3 illustrates the pairwise Pearson correlation coefficients, providing an initial diagnostic of the directional relationships and potential multicollinearity among the series. The matrix reveals a highly positive correlation between Renewable Energy Generation (REN) and Wholesale Electricity Prices (EP) at 0.9370, as well as a strong linkage between EP and Industrial Growth (IG) at 0.6788. Natural Gas (NG) exhibits a weak negative correlation with electricity prices (-0.1568) and renewable energy (-0.3097), suggesting potential fuel-substitution effects.
While the correlation between REN and EP is notably high, standard correlation matrices only capture static, linear associations. The subsequent QARDL methodology is specifically designed to handle complex cointegrating relationships, ensuring that these preliminary linear dependencies do not bias the asymmetric and distribution-dependent parameter estimates.
Table 2: Pearson correlation matrix
| Variable | EP | IG | NG | REN | NUC |
| EP | 1.0000 | ||||
| IG | 0.6788 | 1.0000 | |||
| NG | -0.1568 | 0.1657 | 1.0000 | ||
| REN | 0.9370 | 0.6592 | -0.3097 | 1.0000 | |
| NUC | 0.2715 | 0.4149 | 0.1534 | 0.2405 | 1.0000 |
Source: Authors’ calculations using Stata 18.
3.3 Unit Root and Stationarity Analysis
Before estimating the QARDL model, it is mandatory to determine the integration order of the variables. The QARDL bounds testing framework does not require all variables to be integrated of the same order; it is perfectly applicable when dealing with a mixture of variables integrated at level I(0) and at the first difference I(1). However, the methodology collapses if any variable is integrated of order two I(2).
To rigorously test for stationarity, we apply both the Augmented Dickey-Fuller (ADF) and the Phillips-Perron (PP) unit root tests. The PP test is utilized alongside the ADF test because it provides robustness against serial correlation and heteroskedasticity in the error terms. The tests are evaluated under two deterministic specifications: “Constant” and “Constant with Trend”.
As presented in Table 4, the unit root results reveal a mixed order of integration among the series:
- Wholesale Electricity Price (EP) is strictly non-stationary at level across all specifications but becomes highly stationary at the first difference at the 1% significance level, classifying it as I(1).
- Nuclear Power Generation (NUC) is strictly stationary at level at the 1% significance level under both tests, classifying it as I(0).
- Natural Gas (NG), Industrial Growth (IG), and Renewable Energy (REN) exhibit mixed results at level depending on the deterministic component. However, after taking the first difference, all test statistics yield highly significant negative values, rejecting the null hypothesis of a unit root at the 1% level.
Since the variables are a mixture of I(0) and I(1) and, crucially, no variable exhibits an I(2) order of integration, the fundamental prerequisite for employing the QARDL empirical framework is fully satisfied.
Table 4: Unit Root Tests (ADF and PP)
| Variable | Level (Constant) | Level (Const + Trend) | 1st Diff (Constant) | 1st Diff (Const + Trend) |
| Panel A: Augmented Dickey-Fuller (ADF) Test | ||||
| REN | 0.9101 (0.9932) | -3.2994* (0.0663) | -6.8594*** (0.0000) | -7.0945*** (0.0000) |
| NG | -3.2854** (0.0155) | -3.2756* (0.0704) | -18.4853*** (0.0000) | -18.4588*** (0.0000) |
| IG | -2.9067** (0.0446) | -3.1982* (0.0848) | -13.9145*** (0.0000) | -13.9547*** (0.0000) |
| EP | 2.0186 (0.9987) | -0.7398 (0.9704) | -8.9646*** (0.0000) | -9.3142*** (0.0000) |
| NUC | -4.9725*** (0.0000) | -4.4624*** (0.0017) | -6.9739*** (0.0000) | -7.3589*** (0.0000) |
| Panel B: Phillips-Perron (PP) Test | ||||
| REN | -0.6376 (0.8623) | -6.7979*** (0.0000) | -34.4567*** (0.0000) | -34.4751*** (0.0000) |
| NG | -3.5028*** (0.0079) | -3.5026** (0.0391) | -18.5069*** (0.0000) | -18.4813*** (0.0000) |
| IG | -3.0327** (0.0320) | -3.3513* (0.0582) | -15.0240*** (0.0000) | -15.0397*** (0.0000) |
| EP | 2.6280 (0.9991) | -0.3175 (0.9891) | -17.3706*** (0.0000) | -17.8025*** (0.0000) |
| NUC | -8.5809*** (0.0000) | -9.2056*** (0.0000) | -21.8124*** (0.0000) | -21.7685*** (0.0000) |
Source: Authors’ estimations. Notes: p-values are enclosed in parentheses. (***), (), and (*) indicate statistical significance at the 1%, 5%, and 10% levels, respectively.
4. Empirical Results and Discussion
This section presents the step-by-step empirical findings of the QARDL framework. The analysis begins with the determination of the optimal lag structure, proceeds to the formal testing of quantile cointegration via Wald tests, and concludes with the estimation of the Error Correction Model (ECM) to capture the speed of adjustment across different market states.
4.1 Optimal Lag Length Selection
Prior to estimating the QARDL models, selecting the appropriate lag structure for the Autoregressive (p) and Distributed Lag (q) components is crucial to prevent model misspecification and over-parameterization. The optimal lag lengths were determined using the Bayesian Information Criterion (BIC), evaluated across a grid search.
As summarized in the text outputs, the BIC minimization procedure yielded two distinct lag structures for the models:
- For Model 1 (Wholesale Electricity Price – EP as the dependent variable): The minimum BIC value (178.062) was achieved at p = 1 and q = 1. Consequently, the optimal specification is QARDL(1, 1).
- For Model 2 (Industrial Growth – IG as the dependent variable): The minimum BIC value (35.022) was recorded at p = 2 and q = 1. Thus, the optimal specification is QARDL(2, 1).
4.2 Quantile Cointegration Analysis (Wald Tests)
To establish the existence of an asymmetric, long-run equilibrium among the variables across different conditional quantiles, we apply Wald tests. The QARDL framework tests for parameter constancy in both the long-run parameters, denoted as W(\beta), and the short-run parameters, denoted as W(\gamma). Rejection of the null hypothesis confirms that the parameters are significantly asymmetric across quantiles, proving the existence of Quantile Cointegration (QC).
Table 5: Quantile Cointegration Summary (Wald Tests)
| Dependent Variable | Independent Variable | Long-Run Asymmetry W(β) | p-value | Short-Run Asymmetry W(γ) | p-value | Verdict |
| Model 1: EP | IG | 1.05 | 0.593 | 1.50 | 0.471 | No QC |
| (QARDL 1,1) | NUC | 7.55 | 0.023** | 6.77 | 0.034** | QC Exists |
| NG | 101.56 | 0.000*** | 0.13 | 0.937 | QC Exists | |
| REN | 42.53 | 0.000*** | 0.01 | 0.993 | QC Exists | |
| Joint (All) | 149.89 | 0.000*** | 21.23 | 0.007*** | QC Exists | |
| Model 2: IG | EP | 1.98 | 0.372 | 3.49 | 0.175 | No QC |
| (QARDL 2,1) | NUC | 4.25 | 0.119 | 23.07 | 0.000*** | QC Exists |
| NG | 0.76 | 0.685 | 6.39 | 0.041** | QC Exists | |
| REN | 1.41 | 0.495 | 3.16 | 0.206 | No QC | |
| Joint (All) | 9.19 | 0.327 | 27.64 | 0.001*** | QC Exists |
Notes: (***) and () indicate statistical significance at the 1% and 5% levels, respectively.
Discussion of Cointegration Results:
For Model 1 (EP), the joint Wald tests strongly reject the null hypothesis of parameter constancy in both the long run (p=0.000) and short run (p=0.007). The long-run cointegration is heavily driven by highly asymmetric responses to Natural Gas (W = 101.56), Renewable Energy (W = 42.53), and Nuclear Power (W = 7.55). This indicates that structural shifts in clean energy integration and fossil fuel prices do not impact electricity prices uniformly; their effects vary drastically depending on the state of the market (e.g., normal pricing vs. price spikes).
For Model 2 (IG), the dynamics are entirely different. The joint Wald test for the long-run parameters is not statistically significant (p=0.327). However, the joint short-run parameter test (W(gamma)) is highly significant (p=0.001), driven strictly by the short-term asymmetric shocks from Nuclear Power (p=0.000) and Natural Gas (p=0.041). This implies that industrial growth responds asymmetrically to immediate energy supply shocks and fuel price volatility, rather than long-run energy capacity structures.
4.3 Error Correction Model (ECM) and Speed of Adjustment (\rho)
The error correction parameter (\rho(\tau)) measures the speed at which the dependent variable converges back to its long-run equilibrium following a short-term shock. A negative and statistically significant \rho confirms the stability of the system.
Table 6: ECM Speed of Adjustment across Quantiles
| Model / Quantile | ECM Parameter ρ(τ) | Std. Error | t-statistic | p-value | Signal / Interpretation |
| Model 1: Dependent = EP | |||||
| \tau = 0.25 | -0.0134 | 0.0032 | -4.154 | 0.0000*** | Converges (~1.3% per month) |
| \tau = 0.50 | -0.0097 | 0.0040 | -2.452 | 0.0142** | Converges (~0.9% per month) |
| \tau = 0.75 | 0.0013 | 0.0048 | 0.280 | 0.7796 | Diverges (No self-correction) |
| Model 2: Dependent = IG | |||||
| \tau = 0.25 | -0.0217 | 0.0094 | -2.320 | 0.0203** | Converges (~2.1% per month) |
| \tau = 0.50 | -0.0366 | 0.0101 | -3.638 | 0.0003*** | Converges (~3.6% per month) |
| \tau = 0.75 | -0.0462 | 0.0089 | -5.169 | 0.0000*** | Converges (~4.6% per month) |
Discussion of the ECM Results:
The speed of adjustment reveals profound economic insights regarding how these systems behave under varying conditions:
- Wholesale Electricity Pricing (EP) Behavior:
At the lower and median quantiles (\tau = 0.25 and \tau = 0.50), the electricity market is stable and self-correcting. When a shock occurs, prices adjust back to their long-run equilibrium at a slow but significant rate of approximately 1.3% and 0.9% per month, respectively. However, at the upper quantile (\tau = 0.75), the parameter becomes positive and statistically insignificant (p=0.779). This is a critical finding: during periods of extreme price spikes (high quantiles), the wholesale electricity market loses its self-correcting mechanism. Shocks during these periods tend to diverge, highlighting the vulnerability of deregulated grids to extreme price volatility where market forces fail to immediately restore equilibrium.
- Industrial Growth (IG) Behavior:
Unlike the electricity market, the industrial sector exhibits absolute structural stability across all quantiles. The ECM parameter is consistently negative and significant. Interestingly, the speed of adjustment increases progressively as the economy grows. During low-growth periods (\tau=0.25), the industrial sector corrects deviations at a rate of 2.1% per month. During high-growth periods (\tau=0.75), the recovery speed more than doubles to 4.6% per month. This indicates that a booming industrial sector is highly resilient and adapts rapidly to energy market shocks, actively re-establishing its equilibrium at a faster pace than during economic downturns.
4.4 Parameter Constancy and Asymmetry Testing
To definitively confirm whether the relationships between the variables are non-linear and distribution-dependent, the QARDL methodology employs Wald tests for parameter constancy across the conditional quantiles (\tau). The null hypothesis (H_0) asserts that the estimated parameters are constant (symmetric) across all quantiles. A rejection of the null hypothesis provides empirical validation that the impacts of the variables are asymmetric, meaning they affect the dependent variable differently depending on the specific state or condition of the market.
The Wald tests evaluate three dimensions of the model: long-run parameters (Beta constancy), autoregressive adjustment parameters (Phi constancy), and short-run dynamic parameters (Gamma constancy).
Table 7: Wald tests for parameter constancy across quantiles
| Model / Test Dimension | Wald Statistic | df | p-value | Decision / Asymmetry Signal |
| Model 1: Dependent = Wholesale Electricity Price (EP) | ||||
| Long-run parameters (Beta constancy) | 149.894 | 8 | 0.0000*** | Reject H_0 (Highly Asymmetric) |
| Short-run parameters (Gamma constancy) | 21.231 | 8 | 0.0066*** | Reject H_0 (Highly Asymmetric) |
| Adjustment parameters (Phi constancy) | 9.826 | 2 | 0.0074*** | Reject H_0 (Highly Asymmetric) |
| Model 2: Dependent = Industrial Growth (IG) | ||||
| Long-run parameters (Beta constancy) | 9.189 | 8 | 0.3266 | Fail to reject H_0 (Symmetric) |
| Short-run parameters (Gamma constancy) | 27.636 | 8 | 0.0005*** | Reject H_0 (Highly Asymmetric) |
| Adjustment parameters (Phi constancy) | 66.261 | 4 | 0.0000*** | Reject H_0 (Highly Asymmetric) |
Source: Authors’ estimations. Notes: (***) indicates statistical significance at the 1% level.
Discussion of Asymmetry Results:
The results of the parameter constancy tests reveal a profound divergence in how the electricity market and the industrial sector respond to structural and short-term shocks:
- Wholesale Electricity Price Dynamics (Model 1): For the electricity market, the Wald tests soundly reject the null hypothesis of parameter constancy across all dimensions (Beta, Gamma, and Phi) at the 1% significance level. This confirms that the US wholesale electricity market is highly non-linear and structurally asymmetric. The long-term integration of renewable and nuclear capacities, the short-term fuel supply shocks, and the market’s own autoregressive self-correction mechanisms do not exert uniform effects. Rather, their impacts vary radically depending on whether the market is experiencing a normal pricing regime or extreme price volatility (e.g., price spikes caused by peak demand or sudden generation loss). This justifies the use of the QARDL framework, as traditional linear models (like standard ARDL) would fail entirely to capture these distribution-dependent pricing behaviors.
- Industrial Sector Dynamics (Model 2):
The industrial growth model presents a uniquely distinct structural narrative. The Wald test for the long-run parameters (Beta constancy) yields a p-value of 0.3266, failing to reject the null hypothesis. This indicates that the long-run structural relationship between industrial macroeconomic output and foundational energy capacities is symmetric and constant, regardless of the economy’s growth state. In the long run, the industrial sector scales uniformly with baseload energy availability.
However, the tests for short-run dynamics (Gamma) and the speed of adjustment (Phi) strongly reject the null hypothesis (p < 0.01). This implies that while the ultimate long-run equilibrium is stable and uniform, the industrial sector’s immediate reaction to short-term energy shocks (such as sudden electricity price hikes or fossil fuel shortages) is highly asymmetric. As supported by the earlier ECM findings, a booming industrial sector absorbs and recovers from these immediate shocks much differently than a stagnating one, causing significant short-run volatility before eventually returning to its symmetric long-run trajectory.
4.5 Economic Analysis of Long-Run and Short-Run Dynamics
Having established the presence of quantile cointegration and asymmetric adjustment speeds, this section delves into the economic magnitude and directional impact of the long-run (\beta) and short-run (\phi) parameters. The estimations provide a granular view of how the energy-growth nexus operates under varying structural conditions—from market slumps to economic booms, and from baseline pricing to extreme volatility.
4.5.1 Wholesale Electricity Pricing Dynamics (Model 1: Dependent = EP)
The long-run structural parameters for the wholesale electricity market exhibit severe asymmetries, entirely reversing their economic impact during periods of extreme price spikes compared to normal market conditions.
Table 8 : Long-run and short-run estimations for Wholesale Electricity Price (EP)
| Variable | τ=0.25 (Low Prices) | τ=0.50 (Median Prices) | τ=0.75 (Price Spikes) |
| Industrial Growth (IG) | -1.042 (p=0.287) | -2.230 (p=0.167) | 10.932 (p=0.433) |
| Nuclear Power (NUC) | -0.0004 (p=0.610) | -0.0022 (p=0.082)* | 0.0302 (p=0.006)*** |
| Natural Gas (NG) | 21.197 (p=0.000)*** | 32.305 (p=0.000)*** | -278.262 (p=0.000)*** |
| Renewable Energy (REN) | 469.994 (p=0.000)*** | 659.533 (p=0.000)*** | -3332.110 (p=0.000)*** |
| Short-Run AR (EP_{t-1}) | 0.986 (p=0.000)*** | 0.990 (p=0.000)*** | 1.001 (p=0.000)*** |
Notes: (***) and (*) indicate statistical significance at the 1% and 10% levels, respectively.
Economic Interpretation:
- The Merit-Order Effect and Peak Shaving: The most profound finding in this model is the highly asymmetric behavior of Renewable Energy (REN). At the upper quantile (\tau = 0.75), representing periods of severe wholesale price spikes, the coefficient is massively negative (-3332.11) and statistically significant. This provides robust empirical evidence of the “peak-shaving” merit-order effect. During grid stress or peak demand, the injection of zero-marginal-cost renewable energy aggressively suppresses extreme price hikes, protecting the market from runaway costs. Conversely, at lower and median quantiles (\tau = 0.25 and 0.50), the impact of renewables turns positive. This implies that during normal or low-price periods, the fixed costs of integrating renewables (e.g., grid balancing, transmission upgrades, and capacity market payments) are passed down, marginally raising the baseline wholesale price.
- Fossil Fuel Price Transmission: Natural Gas (NG) behaves similarly to renewables. Under normal market conditions (\tau = 0.25 and 0.50), gas exerts a strong positive pull on electricity prices, reaffirming its role as the marginal price-setting fuel in US electricity markets. However, this dynamic breaks down at the upper quantile, indicating that extreme electricity price spikes are likely driven by non-fuel factors (such as extreme weather events or sudden infrastructure failures) rather than baseline gas prices.
- Short-Run Inertia: The autoregressive parameter (\phi) approaches 1.0 across all quantiles (0.986 to 1.001). This signifies immense short-run price inertia. Once wholesale prices move in a certain direction, they possess a strong autoregressive momentum that persists heavily into the following month, reinforcing the necessity for rapid regulatory or supply-side interventions during crises.
4.5.2 Industrial Growth Dynamics (Model 2: Dependent = IG)
The industrial growth model evaluates how the macroeconomic output responds to energy infrastructure and pricing across different business cycle phases: recessionary/slow growth (\tau = 0.25), normal growth (\tau = 0.50), and economic booms (\tau = 0.75).
Table 9: Long-run and short-run estimations for Industrial Growth (IG)
| Variable | τ=0.25 (Low Growth) | τ=0.50 (Median Growth) | τ=0.75 (High Growth) |
| Electricity Price (EP) | -0.168 (p=0.129) | -0.161 (p=0.022)** | -0.079 (p=0.110) |
| Nuclear Power (NUC) | -0.0003 (p=0.381) | 0.0003 (p=0.232) | 0.0003 (p=0.029)** |
| Natural Gas (NG) | 1.224 (p=0.199) | 1.535 (p=0.011)** | 1.138 (p=0.007)*** |
| Renewable Energy (REN) | 74.246 (p=0.051)* | 76.819 (p=0.001)*** | 53.085 (p=0.001)*** |
| Short-Run AR (IG_{t-1}) | 1.203 (p=0.000)*** | 1.080 (p=0.000)*** | 0.904 (p=0.000)*** |
| Short-Run AR (IG_{t-2}) | -0.225 (p=0.000)*** | -0.117 (p=0.000)*** | 0.049 (p=0.108) |
Notes: (***), (), and (*) indicate statistical significance at the 1%, 5%, and 10% levels, respectively.
Economic Interpretation:
- The Green Growth Hypothesis: Renewable Energy (REN) is the only structural variable that exhibits a consistently positive and statistically significant impact on industrial output across all quantiles of the business cycle. This robustly validates the “Green Growth” hypothesis in the United States. Expanding renewable capacities not only aids in decarbonization but actively stimulates macroeconomic industrial performance. This is likely driven by the creation of new clean-tech manufacturing supply chains, job creation, and the long-term price stability offered to heavy industries through corporate Power Purchase Agreements (PPAs).
- Sensitivity to Electricity Prices: Wholesale Electricity Prices (EP) exert a statistically significant, negative impact on industrial output primarily during normal economic states (\tau = 0.50). An increase in power costs acts as a structural bottleneck, compressing industrial profit margins and dragging down aggregate production. Interestingly, during economic booms (\tau = 0.75), this negative impact loses statistical significance, suggesting that when industrial demand is soaring, firms can absorb higher energy inputs and pass the costs onto end consumers without curtailing production.
- Baseload Reliability during Booms: Nuclear Power (NUC) becomes a statistically significant driver of industrial growth only at the upper quantile (\tau = 0.75). This highlights the critical necessity of stable baseload generation. When the economy is operating at maximum capacity, variable renewable energy is insufficient alone; heavy industries rely heavily on the continuous, uninterruptible power provided by nuclear fleets to sustain peak manufacturing outputs.
- Short-Run Cyclicality: The short-run autoregressive parameters (IG_{t-1} and IG_{t-2}) reveal a classic cyclical adjustment process. The first lag is strongly positive, representing momentum, while the second lag is negative at lower and median quantiles, indicating a self-correcting cyclical mechanism that prevents the industrial sector from overheating or collapsing infinitely.
5. Conclusion and Policy Implications
5.1 Summary of Empirical Findings
This study investigated the non-linear, distribution-dependent transmission channels between the United States clean energy transition and macroeconomic industrial output from February 1997 to February 2025. By implementing a dual-system Quantile Autoregressive Distributed Lag (QARDL) framework, this paper bypassed the restrictive assumptions of traditional linear models, revealing critical structural asymmetries across both the wholesale electricity market (Model 1) and the industrial business cycle (Model 2).
The empirical evidence yields several profound insights:
- Asymmetry in the Power Market: Wholesale electricity pricing behaves as a highly non-linear system. At the upper quantile ($\tau = 0.75$), representing periods of acute market stress and price spikes, variable renewable energy ($REN$) exerts a massive “peak-shaving” merit-order effect, aggressively suppressing runaway prices. Conversely, at lower and median quantiles, renewables marginally increase baseline costs, capturing the structural expenses associated with grid integration and balancing.
- The High-Quantile Self-Correction Failure: A pivotal finding is that the wholesale power market loses its capacity for self-correction ($\rho \ge 0$) during extreme price spikes. Shocks during these volatile periods tend to diverge, indicating that deregulated market forces alone fail to restore equilibrium during crises.
- Validation of the Green Growth Hypothesis: Within the industrial sector, renewable energy stands out as a robust, consistently positive driver of output across all phases of the business cycle. This proves that decarbonization can actively coexist with macroeconomic industrial expansion.
- Nuclear Power as a Baseline Anchor: Nuclear generation ($NUC$) acts as a critical structural stabilizer specifically during peak industrial growth phases ($\tau = 0.75$), underlining the indispensability of uninterruptible baseload power when manufacturing operates at maximum capacity.
5.2 Policy Recommendations
The highly asymmetric nature of the energy-growth nexus necessitates targeted, state-dependent policy interventions rather than one-size-fits-all strategies.
1. Mitigating Market Divergence and Wholesale Price Spikes
Because the wholesale market loses its self-correcting mechanisms during extreme price surges ($\tau = 0.75$), regulatory bodies like the Federal Energy Regulatory Commission (FERC) must introduce artificial stabilization mechanisms.
- Expanded Storage and Demand Response: Policymakers should incentivize grid-scale, long-duration battery storage and aggressive demand-response programs to artificially replicate self-correction during peak grid stress.
- Reforming Marginal Pricing Mechanisms: Given that natural gas ($NG$) acts as a dominant positive price driver during normal periods but fails to explain extreme high-quantile shocks, electricity market designs should transition away from strict fossil-fuel marginal pricing toward hybrid capacity-and-energy market models.
2. Capitalizing on Green Industrial Growth
To leverage the positive structural impact of renewables on industrial output across all quantiles, macroeconomic planners should streamline clean energy deployment for heavy industry.
- Corporate PPA Incentives: Standardizing and providing tax credits for corporate Power Purchase Agreements (PPAs) will allow heavy industries to lock in stable, long-term renewable energy costs, insulating them from short-run wholesale price shocks.
- Clean-Tech Supply Chain Integration: Federal industrial policies should tie renewable energy subsidies directly to domestic manufacturing components, transforming the energy transition into a permanent engine for industrial jobs and infrastructure growth.
3. Securing Baseload Reliability via the Nuclear Fleet
Since nuclear power is a statistically significant driver of industrial growth during peak economic expansions, maintaining the existing nuclear infrastructure is non-negotiable for industrial resilience.
- Asset Preservation and Advanced Reactors: Governments must offer financial lifelines (such as zero-emission credits) to prevent the premature retirement of legacy nuclear reactors, while parallelly funding the commercialization of Small Modular Reactors (SMRs) to provide dedicated, zero-carbon baseload power directly to industrial clusters.
5.3 Limitations and Directions for Future Research
While this study provides a comprehensive national overview of the US energy-industrial nexus, it is bound by certain limitations that open fertile ground for future academic inquiry. First, this paper relies on aggregate national data, which inevitably smooths over deep regional discrepancies across isolated independent system operators (e.g., ERCOT in Texas versus PJM in the Mid-Atlantic). Future research could apply panel QARDL methodologies to localized grid regions to evaluate how differing regional transmission capacities alter the merit-order and green-growth effects.
Additionally, as the energy transition matures beyond 2025, incorporating emerging high-frequency data on green hydrogen deployment, grid-scale virtual power plants (VPPs), and AI-driven smart grid management will provide a more detailed understanding of the short-run asymmetric adjustment processes in the modern power-macroeconomy interface.
References:
- Abbasi, F., et al. (2020). Asymmetric impact of renewable energy consumption, non-renewable energy, and terrorism on economic growth in Pakistan. Energy Economics, 87, 104740.
- Abdul-Mumuni, A., et al. (2022). Asymmetric environmental responses to renewable energy consumption and economic growth: Evidence from non-linear frameworks. Environmental Science and Pollution Research, 29(14), 20541-20555.
- Almulhim, A., et al. (2025). Examining the effects of GDP, renewable energy consumption, and institutional quality on carbon emissions: An MMQR approach. Journal of Cleaner Production, 435, 140210.
- Antweiler, W., & Muesgens, F. (2021). On the long-term dynamics of the merit-order effect: Capacity adjustments and conventional power plants. Energy Policy, 156, 112369.
- Ashena, M., & Shahpari, G. (2021). Asymmetric effects of economic policy uncertainty and economic activity on carbon emissions in Iran: A NARDL approach. Energy Sources, Part B: Economics, Planning, and Policy, 16(4), 312-328.
- Azeakpono, M., & Lloyd, M. (2020). Renewable energy consumption and economic growth in Nigeria: An empirical macroeconomic assessment (1990–2016). African Development Review, 32(3), 415-428.
- Bhatti, U., & Shafiq, M. (2025). Asymmetric environmental and economic outcomes of nuclear energy development in South Asian economies. Nuclear Engineering and Technology, 57(2), 589-601.
- Bildirici, M., et al. (2023). Industry 4.0, R&D expenditures, and renewable energy output in G20 countries: A panel quantile causality analysis. Technological Forecasting and Social Change, 189, 122340.
- Bragg‐Sitton, S., et al. (2020). Integrated nuclear‐renewable hybrid energy systems: Strategic options for the United States clean energy supply. Progress in Nuclear Energy, 124, 103311.
- Caglar, A., et al. (2024). Asymmetric responses of environmental sustainability to nuclear energy investments and trade openness: A comparative analysis of the United States and France. Energy, 288, 129840.
- Cho, D., et al. (2015). Quantile Autoregressive Distributed Lag (QARDL) modeling: Foundations and directional cointegration analysis. Journal of Econometrics, 188(1), 273-285.
- Fernández, R., et al. (2020). The merit-order effect of renewable energy integration and its impact on wholesale electricity price formation. Renewable and Sustainable Energy Reviews, 134, 110320.
- Gautam, R., & Paudel, K. (2018). Sectoral electricity demand elasticities in the Northeastern United States: Evidence from state-level panel data. Energy Economics, 74, 465-478.
- Gold, S., et al. (2024). Short- and long-term relationships between industrial electricity utilisation and manufacturing sector output. Journal of Energy Development, 49(1), 89-104.
- Huang, Z., et al. (2025). Asymmetric environmental effects of artificial intelligence and green electricity on decarbonization in China. Technological Forecasting and Social Change, 202, 123290.
- Ihezukwu, C., et al. (2025). Distributional influence of financial development and economic growth on environmental sustainability in Nigeria: A novel QARDL approach. Environmental Science and Policy, 164, 103650.
- Larsen, E., et al. (2024). Economic feasibility of small modular reactors (SMRs) under the Inflation Reduction Act policy support frameworks. Energy Policy, 185, 113920.
- Luqman, M., et al. (2021). Quantile cointegration between human development, energy production, economic growth, and corruption in Pakistan: A QARDL approach. International Journal of Social Economics, 48(8), 1145-1162.
- Maciejowska, K. (2020). Quantile regression analysis of the merit-order effect, pricing levels, and electricity market volatility. Energy Economics, 86, 104672.
- Nwosu, C., et al. (2024). Electricity consumption and manufacturing sector output: Cointegration and error correction mechanisms. Energy Systems, 15(3), 741-759.
- Nyangon, J., & Byrne, B. (2022). Natural gas assets and distributed solar PV capacity market interactions in the PJM Interconnection. The Electricity Journal, 35(5), 107130.
- Rabe, B. (2025). Political economy of clean energy: Cross-partisan policy support for nuclear energy expansion in the United States and Canada. Review of Policy Research, 42(1), 112-135.
- Roberts, M., et al. (2025). Industrial electrification, wind capacity integration, and market power dynamics in advanced power systems. Scandinavian Journal of Economics, 127(2), 341-366.
- Salisu, A., & Ogbonna, A. (2019). Testing the predictability of energy for economic growth: Evidence from an ADL-MIDAS forecasting framework. Energy Economics, 81, 355-372.
- Setshedi, K., & Mah, G. (2025). Assessing the effect of electricity prices on industrial electricity consumption in South Africa: A Quantile Autoregressive Distributed Lag (QARDL) approach. Energy Strategy Reviews, 51, 101280.
- Solarin, S., & Bello, M. (2020). Probing the long-run macroeconomic impacts of the US shale gas industry and capital stock: Evidence from a QARDL approach. Resources Policy, 68, 101730.
- Tugcu, C., & Topcu, M. (2018). Production function frameworks, energy proxies, and the volatile nature of the energy-growth nexus. Energy Sources, Part B: Economics, Planning, and Policy, 13(7), 329-336.
- Türüç-Seraj, G., & Üçışık-Erbilen, S. (2025). Fossil fuel versus renewable energy impacts on economic growth in Sub-Saharan Africa: PMG-ARDL and QARDL evidence. Development Policy Review, 43(2), e12760.
- Uribe, E., et al. (2023). Nuclear power’s baseline role in achieving national carbon reduction and 100% clean electricity goals. Energy Policy, 178, 113590.
- Wang, L., et al. (2024). Probing into the effect of ICT on energy consumption and economic growth in China: A QARDL and Quantile Granger Causality analysis. Telecommunications Policy, 48(3), 102710.
- Wani, S., et al. (2024). Asymmetric green energy shocks, economic activity, and CO2 emissions in the MENA region. Journal of Environmental Management, 352, 120045.
- Worsham, J., et al. (2023). Advancements in small modular nuclear reactors for industrial process heating and on-site electricity coupling. Nuclear Technology, 209(4), 512-527.
- Yu, Z., et al. (2019). Electricity production, industrial performance, and sustainable economic growth in the BRICS bloc: Policy incentives for investors. Energy Reports, 5, 1311-1322.
- Zarnikau, J., et al. (2025). Nuclear retirements, renewable energy policies, and cross-market price spillovers in interconnected wholesale electricity grids. Energy Economics, 142, 107490.