DOI:https://doi-0004.org/6812/17904096225741
BOUCHIKHI Ahmed 1,*, TIGRINE Imene 2, RAHAL Mourad 3, BOUAMRA Hacene 4
1 University Of Tamanghasset, DIDDUZOF Laboratory, Algeria. E-Mail: ahmed.bouchikhi@univ-tam.dz
2 University of Blida 2 – Lounici Ali, Algeria. E-Mail: pep.ar.tigrine.imene@gmail.com.
3 Chahid Cheikh Laarbi Tebessi University, Tebessa, Laboratory of Economic Diversification Strategies for Achieving Food, Health, and Energy Security in Algeria, Algeria. E-Mail: mourad.rahal@univ-tebessa.dz.
4 Chahid Cheikh Laarbi Tebessi University, Tebessa, Laboratory of Economic Diversification Strategies for Achieving Food, Health, and Energy Security in Algeria, Algeria. E-Mail: hacene.bouamra@univ-tebessa.dz.
Received: 14/08/2026 ; Published: 26/09/2026
Abstract
Maintaining sovereign fiscal sustainability while preserving policy headroom has become a critical challenge for global macroeconomic governance. This study investigates the non-linear and asymmetric transmission mechanisms between public debt accumulation, financial development, and fiscal space within a noise-filtered environment. To overcome the limitations of traditional linear estimations and high-frequency market noise, we employ a novel hybrid Wavelet-Based Non-linear Autoregressive Distributed Lag (W-NARDL) framework. By integrating a non-decimated Haar à trous wavelet transform ($J=7$) with soft-thresholding signal processing into a non-linear error-correction model, the study purges transient time-series volatility while isolating short- and long-run dynamic asymmetries via partial sum decompositions. The empirical results confirm a robust long-run cointegrating relationship among the variables. Crucially, the analysis uncovers significant structural asymmetry in sovereign debt dynamics: while short-run public debt expansion provides temporary fiscal relief, long-run fiscal consolidation triggers a counter-intuitive contraction in fiscal headroom—a phenomenon termed the Fiscal Consolidation Paradox. Furthermore, comparative benchmarking demonstrates the clear empirical superiority of the W-NARDL model over conventional unfiltered NARDL specifications in terms of explanatory power and model parsimony. These findings highlight the necessity of designing growth-enhancing fiscal strategies and aligning sovereign debt management with monetary policy to safeguard long-run fiscal capacity.
Keywords: Fiscal Space, Public Debt, Financial Development, Wavelet Denoising, W-NARDL, Asymmetry, Fiscal Consolidation Paradox.
JEL Classification: C32, E62, H63, O16.
Introduction
In an era characterized by compounding economic shocks, monetary tightening, and historic public debt levels, maintaining sovereign fiscal sustainability while preserving policy flexibility has become a central challenge for global macroeconomic governance. At the heart of this dilemma lies the concept of fiscal space, defined as the budgetary headroom available to a government to finance public expenditures without endangering sovereign debt sustainability or financial stability. While public debt accumulation and financial sector evolution are widely acknowledged as pivotal determinants of fiscal capacity, the precise dynamic channels through which they interact remain a subject of intense debate, spanning Keynesian multiplier effects, Ricardian equivalence constraints, and financial market feedback loops.
Despite an extensive body of literature on fiscal policy dynamics, conventional empirical frameworks suffer from two fundamental methodological limitations. First, traditional linear econometric models implicitly assume that fiscal space responds symmetrically to macro-financial changes, ignoring behavioral loss aversion and the asymmetric risk perceptions of financial markets during periods of fiscal expansion versus fiscal consolidation. Second, macro-financial time series are inherently contaminated by high-frequency market noise and transient volatility, which can distort parameter estimates and obscure true long-run equilibrium relationships. These limitations give rise to a critical research problem concerning the extent to which public debt dynamics and financial development exert non-linear, asymmetric effects on fiscal headroom across short- and long-run horizons when high-frequency noise is explicitly filtered.
To address this issue, this study develops a hybrid Wavelet-Based Non-linear Autoregressive Distributed Lag (W-NARDL) framework. By integrating a non-decimated Haar à trous wavelet transform with a soft-thresholding operator into the non-linear ARDL model of Shin et al. (2014), this approach purges high-frequency noise while simultaneously capturing short- and long-run dynamic asymmetries through partial sum decompositions of positive and negative shocks. This paper contributes to the literature by establishing a noise-filtered econometric framework tailored for sovereign risk analysis, disentangling the structural consequences of debt expansion from fiscal consolidation, and offering dynamic insights for debt management and monetary-fiscal policy coordination.
The remainder of this paper is organized as follows: Section 2 presents the theoretical and empirical literature review; Section 3 details the econometric methodology and model specification; Section 4 reports the empirical results and economic discussion; and Section 5 concludes with key policy implications.
1. Theoretical Literature Review
1.1 Defining Fiscal Sustainability: From Stock to Flow Metrics
The theoretical conceptualization of fiscal sustainability has evolved significantly in recent macroeconomic literature. Traditionally, fiscal sustainability is defined as a state wherein a government’s debt-to-GDP ratio stabilizes or declines over a projected horizon, a stock-based metric widely operationalized by institutions such as the U.S. Treasury Office of Management and Budget and the Government Accountability Office (Treasury, 2026). However, contemporary theoretical frameworks argue that this stock-centric perspective obscures the underlying cash-flow dynamics that genuinely constrain fiscal policy formulation (Eichengreen et al., 2026).
Recent paradigms emphasize that a government’s capacity to service its debt obligations—specifically, debt-service costs relative to available revenues and economic growth rates—is a far more accurate theoretical determinant of sustainability than absolute debt thresholds (Eichengreen et al., 2026). By shifting the focus from a stock metric (debt-to-GDP) to a flow metric (interest costs-to-GDP), economic theory better aligns fiscal sustainability with the actual intertemporal government budget constraint (Eichengreen et al., 2026). The fundamental budget constraint dictates that when the interest-growth differential (the gap between borrowing costs and real economic growth) is positive, governments must generate primary surpluses proportional to the debt stock to stabilize debt levels (Eichengreen et al., 2026). Theoretical debates continue regarding whether positive fiscal reactions to rising debt definitively prove long-term sustainability, as endogeneity concerns suggest these dynamics are jointly determined by underlying economic conditions and prevailing policy preferences (Reis, 2022).
1.2 The Bidirectional Fiscal-Financial Nexus
The theoretical literature establishes a robust, bidirectional mechanism between fiscal sustainability and financial sector development. A fiscally solvent government fosters broad market confidence, diminishes sovereign risk premia, and acts as a catalyst for financial sector deepening (Jiménez-Sotelo, 2025). Conversely, a highly developed financial sector efficiently absorbs government borrowing, acts as a primary transmission channel for monetary policy, and mobilizes domestic savings to fund public expenditures (Jiménez-Sotelo, 2025).
Furthermore, financial development theoretically enhances a government’s tax mobilization capacity; deeper financial intermediation improves the collection of both direct and indirect taxes, thereby structurally expanding fiscal space (Lompo, 2023). However, this relationship is state-dependent (Dinh et al., 2024). The theoretical fiscal-financial nexus literature emphasizes that adequate fiscal space is an absolute prerequisite for maintaining financial stability, as these fiscal buffers are necessary for governments to intervene effectively during banking crises (Borio et al., 2023).
1.3 Financial Stability as an Endogenous Constraint on Fiscal Space
Modern theoretical models explicitly integrate financial stability into fiscal sustainability frameworks, positing that fiscal space is endogenously constrained by financial market fragility rather than just debt levels (Zampolli, 2026). Even when conventional debt-service metrics appear manageable, fiscal space can suddenly contract if financial intermediation is thin or unstable (GAO, 2022). The theoretical literature identifies four primary amplification mechanisms that constrain fiscal space:
- The Bank-Sovereign Nexus: Government debt held by domestic banks inextricably ties sovereign solvency to bank health, meaning stress in one sector directly amplifies stress in the other.
- Original Sin Redux: When a government is forced to borrow in foreign currencies, exchange rate depreciation automatically and severely escalates the real debt burden.
- Duration Matching and Rollover Risk: Structural mismatches between the maturities of assets and liabilities generate acute rollover risks for the borrowing government.
- Deleveraging in Repo Markets: During periods of financial stress, margin calls and fire sales compress asset values, driving systemic losses that rapidly deplete fiscal maneuvering room (Zampolli, 2026).
2. Empirical Literature Review
2.1 The Trajectory of U.S. Public Debt and Structural Breaks
Empirical investigations into U.S. public debt reveal distinct historical phases governing its sustainability. From 1792 through 2003, the U.S. benefited from a robust “growth dividend” where economic growth routinely exceeded interest rates, fundamentally supporting long-term fiscal sustainability (Bohn, 2005). During this extended span, empirical data demonstrates strong, positive fiscal reactions to accumulating debt (Bohn, 2005).
However, time-varying parameter models identify a critical structural break around 2005 (Nguyen et al., 2017). Post-2005, the fiscal reaction function inverted; as the debt-to-GDP ratio rose, primary surpluses shifted to a negative response, a deterioration that severely intensified during the global financial crisis (Nguyen et al., 2017). Further empirical modeling using Markov-switching frameworks indicates that the U.S. government does not stabilize debt continuously, but rather cycles between regimes of fiscal tightening and regimes of expansionary, debt-destabilizing policy (Aldama & Creel, 2019). Threshold-based research suggests that while the U.S. currently experiences only minor adverse growth effects at its 100 percent debt-to-GDP ratio, it is on a trajectory to breach critical thresholds (approaching 160 percent) where sovereign crisis risks accelerate (Schmid, 2019). If policy adjustments are not enacted, the capacity to stabilize debt via fiscal reaction will be severely tested, risking inflation, financial repression, or default (GAO, 2025).
2.2 Asymmetric Effects in Fiscal and Debt Dynamics
A highly significant empirical consensus has emerged indicating that debt accumulation and debt reduction exert asymmetric impacts on economic and fiscal outcomes.
- Private and External Debt: Empirical analyses show that household debt growth heavily supports income growth primarily in low-debt, low-income cons, whereas corporate debt exhibits negative growth impacts in highly indebted, richer economies (Liaqat & Ahmed, 2023). Similarly, positive changes (increases) in external debt trigger significant negative effects on GDP growth, while debt reduction yields significant positive growth effects (Aloulou et al., 2023).
- Distributional and Credit Shocks: Following credit supply shocks, household borrowing expands rapidly (roughly 1.5 percent over three years), but deleveraging in response to credit tightening is significantly slower and smaller in magnitude (Finck & Rudel, 2023). Furthermore, austerity-driven fiscal consolidations spike income inequality sharply when private debt is high, but have negligible distributional impacts when private debt is low (Klein & Winkler, 2017).
- Public Debt: Using NARDL frameworks, empirical evidence from Jordan demonstrates that a 1 percent increase in public debt reduces GDP growth by 0.08 percent, while a 1 percent decrease only stimulates growth by 0.04 percent (Aljaloudi & Ibrahim, 2024). This 2:1 asymmetry proves that the economic costs of debt accumulation heavily outweigh the benefits of equivalent debt reduction.
These asymmetries are empirically driven by financial frictions that magnify crisis reactions and delay recoveries (Ordoñez, 2013), as well as occasionally binding constraints on international borrowing that create steepness in business cycles (Li & Dressler, 2011). Dynamic Stochastic General Equilibrium (DSGE) models further corroborate that high-debt economies, despite strong intermediation, respond more violently to shocks and recover much slower (Burriel et al., 2020).
2.3 Methodological Innovations in Sustainability Measurement
Traditional stationarity tests (ADF, KPSS) frequently fail to capture the nuances of fiscal sustainability due to heteroskedasticity and an inability to map fiscal reaction functions (Bohn, 2005). To overcome linear constraints, the Nonlinear Autoregressive Distributed Lag (NARDL) approach, pioneered by Shin et al. (2014), partitions independent variables into positive and negative partial sums to detect asymmetric short- and long-run dynamics without requiring prior cointegration knowledge (Hussein & Hmood, 2024).
To address non-stationarity, regime shifts, and structural breaks inherent in fiscal time series, empirical research increasingly relies on Wavelet Analysis (Masset, 2015; Lock & Yaakob, 2026). By employing Continuous Wavelet Transforms (CWT) and Multiresolution Analysis (MRA), researchers can decompose series into distinct time-frequency domains (Nguyen & He, 2015; Kılıç & Uğur, 2023; Masset, 2008). This methodology reveals that debt and fiscal outcomes interact heterogeneously across short-run business cycles versus long-run trends (Bhandari, 2020).
2.4 Unresolved Gaps in the Empirical Literature
Despite substantial methodological advancements in modeling fiscal dynamics, several critical gaps remain unresolved within the empirical literature:
- Time-Scale Heterogeneity in Debt Asymmetries: Most NARDL studies estimate a constant asymmetry over the entire sample period, leaving a void in understanding whether the magnitude or sign of debt asymmetry fluctuates across different time horizons. It remains unclear if debt accumulations suppress growth more severely at high-frequency business cycles or across low-frequency secular trends. The deployment of Wavelet-NARDL hybrid models—combining asymmetric decomposition with time-frequency filtering—remains an entirely unexplored frontier in the debt-sustainability literature.
- Joint Modeling of Debt Asymmetries and Financial Development: While existing research independently examines how financial development and public debt affect economic growth, literature that models how financial development explicitly conditions the asymmetry of debt shocks is scarce. It is not yet empirically established whether deeper financial systems amplify or dampen the asymmetric impacts of public debt fluctuations. State-dependent NARDL models, wherein the strength of the asymmetry is a function of prevailing financial conditions, represent a significant gap.
- Specification of Fiscal Space Constraints: The contemporary fiscal-financial nexus literature theoretically identifies financial stability as a binding constraint on fiscal space; however, the empirical quantification of this constraint within the U.S. con is remarkably limited. While precise estimations of fiscal space contraction under adverse financial conditions are prevalent for small open economies and crisis-prone states, equivalent empirical benchmarks for the U.S. macroeconomic environment during non-crisis periods are lacking.
- Endogenous Debt Composition Effects: The observed asymmetry in debt dynamics may be partially driven by underlying shifts in debt maturity profiles and currency composition. For instance, the accumulation of short-term debt obligations may precipitate more severe negative economic impacts compared to equivalent increases in long-term debt. Current NARDL applications predominantly treat public debt as a homogenous, aggregate variable, thereby failing to disentangle these highly consequential compositional effects.
- Interaction Between Monetary and Fiscal Policy: Existing NARDL and wavelet-based studies typically apply reduced-form models that treat macroeconomic variables as exogenous. Consequently, the endogenous interplay between monetary policy interventions (e.g., Federal Reserve interest rate adjustments and quantitative easing) and fiscal sustainability remains systematically underexplored within asymmetric frameworks. A vital unresolved question is how dynamic shifts in central bank policy influence the elasticity of the fiscal response to public debt shocks.
- Regional and Distributional Effects: The overwhelming majority of fiscal sustainability research is concentrated exclusively at the national macroeconomic level, leaving the distributional impacts across income cohorts and regional economies underexamined. Although extant evidence indicates that fiscal austerity sharply exacerbates income inequality when private debt levels are elevated, empirical investigations into how these asymmetric dynamics manifest and constrain fiscal sustainability at state and subnational levels remain exceedingly sparse.
3. Econometric Methodology and Model Specification
3.1. Introduction to the Empirical Framework
To capture the non-linear, time-varying, and asymmetric transmission mechanisms between sovereign debt accumulation, financial development, and fiscal capacity, this study employs a hybrid Wavelet-Based Non-linear Autoregressive Distributed Lag (W-NARDL) framework. Traditional linear econometric frameworks often fail to account for structural asymmetries and high-frequency noise inherent in macro-financial time series.
By integrating maximum overlap non-decimated wavelet transform (à trous wavelet algorithm) with the non-linear ARDL bounds testing methodology developed by Shin, Yu, and Greenwood-Nimmo (2014), this approach decomposes time series into trend and noise components while allowing for positive and negative structural shocks to exert differential impacts across both short- and long-run horizons.
3.2. Definition and Description of Variables
The dataset comprises high-frequency quarterly macro-financial observations. Table 0 summarizes the operational definitions, measurement units, expected theoretical signs, and economic roles of all variables included in the econometric model.
Table 01: Description and Classification of Study Variables
| Variable Code | Variable Name | Operational Definition & Measurement | Theoretical Role / Expectation |
| FS | Fiscal Space | Quantitative index measuring budgetary headroom and debt sustainability margin relative to tax base capacity. | Dependent Variable (Y) |
| PD | Public Debt | Total gross federal/public debt outstanding expressed as a percentage of nominal GDP (Debt-to-GDP ratio %). | Core Explanatory Variable (Asymmetric Decomposed |
| FD | Financial Development | Composite metric aggregating financial market depth, institutional efficiency, and credit allocation efficiency. | Core Explanatory Variable (Asymmetric Decomposed |
| EG_growth | Economic Growth | Real Gross Domestic Product (GDP) annualized quarterly growth rate (%). | Control Variable (Counter-cyclical / Automatic Stabilizer) |
| INF | Inflation Rate | Annualized percentage change in the Consumer Price Index (CPI %). | Control Variable (Monetary environment & debt erosion) |
| INT | Interest Rate | Benchmark short-term central bank / treasury yield policy rate (%). | Control Variable (Sovereign cost of borrowing) |
3.3. Mathematical Formulation of the W-NARDL Model
Step 1: Wavelet Denoising Process
Prior to estimation, each original time series is filtered using a non-decimated Haar à trous wavelet transform (HTW) with soft thresholding (Donoho, 1995) at decomposition level
:
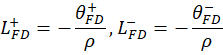
where denotes the wavelet decomposition operator,
represents the soft thresholding operator applied at universal scale threshold
is the resulting denoised time series used for econometric modeling.
Step 2: Partial Sum Decompositions for Asymmetry
To account for non-linear structural asymmetries, the primary explanatory variables (Public Debt and Financial Development
) are decomposed into partial sum processes of positive (
) and negative (
) cumulative changes:
Step 3: The Unrestricted W-NARDL Error Correction Model (ECM)
Combining the wavelet-denoised variables with partial sum decompositions yields the unrestricted W-NARDL error-correction specification:
where represents the vector of macroeconomic control variables, \rho denotes the error-correction speed-of-adjustment parameter, and
is a spherical error term.
Step 4: Long-Run Multipliers and Asymmetry Hypotheses
The long-run asymmetric impacts of positive and negative shocks in public debt and financial development on fiscal space are derived as:
Null hypotheses of long-run and short-run symmetry are formally tested via Wald tests:
- Long-Run Symmetry (
):
- Short-Run Cumulative Symmetry (
):
4. Empirical Results and Discussion
4.1. Descriptive Statistics and Unit Root Tests
The empirical investigation commences with an evaluation of the statistical properties of the variables under study. Table 1 reports the descriptive statistics for the primary dependent variable, Fiscal Space (FS), the decomposed variables of interest—Public Debt (PD) and Financial Development (FD)—and the macroeconomic control variables: Economic Growth (EG_growth), Inflation (INF), and Interest Rates (INT).
Table 1: Descriptive Statistics of the Variables
| Variable | Observations | Mean | Std. Dev. | Min | Max |
| PD | 225 | 66.0923 | 29.5696 | 30.6033 | 132.6629 |
| FD | 225 | 130.2108 | 24.7158 | 89.2000 | 172.0000 |
| FS | 225 | 3.0816 | 3.3480 | -1.2643 | 28.0788 |
| INF | 221 | 3.9555 | 2.8895 | -1.6070 | 14.4258 |
| INT | 225 | 5.9558 | 3.0921 | 0.6500 | 14.8500 |
| EG_growth | 224 | 0.6776 | 1.0743 | -8.2043 | 7.4758 |
The descriptive results highlight significant temporal variation across all series. The public debt ratio (PD) averaged 66.09% of GDP with a substantial standard deviation of 29.57%, ranging between a minimum of 30.60% and a peak of 132.66%, capturing major structural shifts in sovereign debt accumulation. Fiscal Space (FS) recorded a sample mean of 3.0816 points, dropping to a negative minimum of -1.2643, reflecting periods of severe fiscal distress and budgetary constraints. Financial Development (FD) fluctuated between 89.20 and 172.00, with a mean of 130.21.
To verify the integration properties of the series and satisfy the prerequisite for Non-linear Autoregressive Distributed Lag (NARDL) modeling—specifically ensuring no variable is integrated of order I(2)—the Augmented Dickey-Fuller (ADF) unit root test was conducted.
Table 2: Augmented Dickey-Fuller (ADF) Unit Root Test Results
| Variable | Level Z(t) | p-value | First Difference Z(t) | p-value | Integration Status |
| FS | -6.125 | 0.0000 | -19.399 | 0.0000 | I(0) |
| PD | -2.042 | 0.5782 | -16.794 | 0.0000 | I(1) |
| FD | 0.616 | 0.9970 | -6.811 | 0.0000 | I(1) |
| EG_growth | -15.065 | 0.0000 | -26.820 | 0.0000 | I(0) |
| INF | -2.467 | 0.3445 | -9.926 | 0.0000 | I(1) |
| INT | -1.974 | 0.6158 | -11.757 | 0.0000 | I(1) |
Note: ADF critical values at 1% and 5% significance levels are -3.999 and -3.433 for levels, and -3.469 and -2.882 for first differences, respectively.
The ADF unit root test results in Table 2 confirm a mixed order of integration, I(0) and I(1). Fiscal Space (FS) and Economic Growth (EG_growth) are stationary at levels I(0) at the 1% significance level (p = 0.0000). Conversely, Public Debt (PD), Financial Development (FD), Inflation (INF), and Interest Rates (INT) exhibit a unit root at levels but become stationary after taking the first difference I(1). Because no variable is I(2), the dataset satisfies the necessary condition for bounds testing and NARDL modeling.
4.2. Wavelet-Based Denoising Analysis
To remove high-frequency noise and transient fluctuations without sacrificing structural non-linear features, the time series were filtered using a non-decimated Haar à trous wavelet (HTW) transformation with a soft thresholding operator, following Donoho (1995).
Table 3: Wavelet Denoising Summary
| Variable | Decomposition Level (J) | Noise Std. Dev. σnoise | Threshold λ | SD Reduction (%) |
| FS | 7 | 0.1182 | 0.3883 | 12.86% |
| PD | 7 | 0.4463 | 1.4666 | 7.35% |
| FD | 7 | 0.4448 | 1.4614 | -3.44% |
| EG_growth | 7 | 0.3779 | 1.2418 | 22.19% |
| INF | 7 | 0.3024 | 0.9937 | 50.70% |
| INT | 7 | 0.2001 | 0.6576 | 36.35% |
The summary statistics in Table 3 indicate that a 7-level decomposition (J=7) effectively purges high-frequency noise, most notably for Inflation (INF, 50.70% SD reduction), Interest Rates (INT, 36.35%), Economic Growth (EG_growth, 22.19%), and Fiscal Space (FS, 12.86%). This denoising step isolates the true underlying economic signal, optimizing the efficiency of downstream asymmetric econometric estimations.
4.3. W-NARDL Model Selection and Cointegration Bounds Test
Evaluating 12,500 model specifications via the Bayesian Information Criterion (BIC) identified W-NARDL(3, 2, 1, 2, 0, 0) as the optimal specification.
Table 4: Model Selection and Goodness-of-Fit Metrics (W-NARDL)
| Metric | Value | Metric | Value |
| Model Specification | W-NARDL(3, 2, 1, 2, 0, 0) | BIC | -365.5174 |
| R-squared (R^2) | 0.9738 | AIC | -456.7746 |
| Adjusted R-squared ( | 0.9702 | Log-Likelihood | -52.5224 |
| Durbin-Watson (d) | 2.0533 | Observations Used | 217 |
The model demonstrates exceptional goodness-of-fit, with an of 0.9738 and an Adjusted
of 0.9702, indicating that 97.38% of the variation in fiscal space is explained by the denoised asymmetric system.
To evaluate long-run levels relationships under Case III (unrestricted intercept, no trend), the Pesaran, Shin, and Smith (PSS, 2001) bounds testing procedure was conducted.
Table 5: PSS Bounds Test for Cointegration (W-NARDL)
| Test Statistic | Calculated Value | Decision (5% Level) | Decision (1% Level) |
| 10.3412 | Cointegration | Cointegration | |
| -7.1582 | Cointegration | Cointegration | |
| 8.7677 | Cointegration | Cointegration |
Asymptotic Critical Value Bounds (PSS 2001, Case III, k=7):
- 5% Level:
- 1% Level:
The calculated statistic of 10.3412 comfortably exceeds the upper bound I(1) critical value of 4.26 at the 1% significance level. Furthermore, the
statistic (-7.1582) is significantly more negative than the 1% upper bound. We therefore reject the null hypothesis of no level relationship, confirming a stable, non-linear long-run cointegrating relationship among fiscal space, public debt, financial development, and the control variables.
4.4. Short-Run and Long-Run Asymmetric Dynamics
Table 6 presents the error-correction model (ECM) estimation results for the short-run dynamics (Panel A) and long-run level coefficients (Panel B).
Table 6: W-NARDL Estimation Results (Dependent Variable: )
| Variable | Coef. | Std. Err. | t-stat | p-value | Significance | |
| Panel A: Short-Run Dynamics | ||||||
| 0.4050 | 0.0431 | 9.389 | 0.0000 | *** | ||
| -0.1302 | 0.0422 | -3.084 | 0.0024 | ** | ||
| 0.1398 | 0.0433 | 3.226 | 0.0015 | ** | ||
| 0.5831 | 0.0355 | 16.424 | 0.0000 | *** | ||
| -1.1549 | 0.1839 | -6.279 | 0.0000 | *** | ||
| -0.0475 | 0.0784 | -0.605 | 0.5457 | |||
| 0.8009 | 0.1716 | 4.667 | 0.0000 | *** | ||
| 0.0303 | 0.0703 | 0.430 | 0.6673 | |||
| 0.4748 | 0.1263 | 3.760 | 0.0002 | *** | ||
| 0.2489 | 0.1043 | 2.387 | 0.0180 | * | ||
| 0.1254 | 0.1359 | 0.923 | 0.3572 | |||
| -0.2655 | 0.1123 | -2.364 | 0.0191 | * | ||
| -0.2323 | 0.1231 | -1.887 | 0.0607 | . | ||
| -1.9009 | 0.1975 | -9.625 | 0.0000 | *** | ||
| 0.7576 | 0.1263 | 5.997 | 0.0000 | *** | ||
| 0.0563 | 0.0852 | 0.661 | 0.5097 | |||
| -0.0962 | 0.1366 | -0.704 | 0.4822 | |||
| Panel B: Long-Run Levels & ECM | ||||||
| -0.2278 | 0.0318 | -7.158 | 0.0000 | *** | ||
| 0.0010 | 0.0100 | 0.103 | 0.9182 | |||
| -0.0513 | 0.0118 | -4.356 | 0.0000 | *** | ||
| -0.0076 | 0.0049 | -1.535 | 0.1265 | |||
| -0.0139 | 0.0203 | -0.683 | 0.4954 | |||
| -0.1639 | 0.1791 | -0.915 | 0.3613 | |||
| 0.0367 | 0.0276 | 1.330 | 0.1851 | |||
| -0.0475 | 0.0292 | -1.625 | 0.1058 | |||
| Constant | 0.6662 | 0.5955 | 1.119 | 0.2647 | ||
Significance codes: *** p<0.001, p<0.01, * p<0.05, . p<0.1
The Error Correction Term (ECM) parameter is negative and highly statistically significant , p = 0.0000). This confirms that approximately 22.78% of short-run disequilibria relative to the long-run equilibrium path are corrected in each period.
To test for short-run and long-run structural asymmetry, cumulative multipliers and Wald hypothesis tests were calculated (Table 7).
Table 7: Short-Run and Long-Run Multipliers and Wald Tests for Asymmetry
| Variable / Component | Short-Run Estimate (SR) | p-value | Long-Run Estimate (LR) | p-value | Wald Test for Asymmetry |
| Public Debt (PD) | |||||
| – Positive Shocks (+) | 0.5659 | 0.0000 *** | 0.0045 | 0.9180 | SR Asymmetry: |
| – Negative Shocks (-) | 0.1209 | 0.4774 | -0.2253 | 0.0002 *** | LR Asymmetry: |
| Financial Dev. (FD) | |||||
| – Positive Shocks (+) | -0.0166 | 0.8110 | -0.0332 | 0.1575 | SR Asymmetry: F = 0.4270 (p = 0.5143) |
| – Negative Shocks (-) | -0.1069 | 0.3125 | -0.0609 | 0.4993 | LR Asymmetry: |
| Economic Growth (EG) | -1.0876 | 0.0023 ** | -0.7195 | 0.3888 | – |
| Inflation (INF) | 0.0563 | 0.5097 | 0.1611 | 0.1886 | – |
| Interest Rate (INT) | -0.0962 | 0.4822 | -0.2083 | 0.1310 | – |
Key Asymmetry Findings:
The Wald tests reject the null hypothesis of symmetry for Public Debt (PD) in both the short run (F = 5.5171, p = 0.0199) and the long run .
- Short-Run: A positive debt shock
expands fiscal space by 0.5659 units (p < 0.001), whereas negative debt changes
exert no statistically significant immediate impact (0.1209, p = 0.4774).
- Long-Run: The relationship reverses sharply. A reduction in debt (\{PD}^-) leads to a statistically significant contraction in fiscal space (
= -0.2253, p = 0.0002). In contrast, long-run debt increases
yield a statistically negligible effect (0.0045, p = 0.9180).
- Financial Development (FD): No statistically significant short-run (p = 0.5143) or long-run (p = 0.7716) asymmetric impacts on fiscal space were detected.
4.5. Dynamic Multipliers Analysis
Dynamic multipliers capture the horizon-by-horizon trajectories () through which fiscal space adjusts to positive and negative unit shocks in public debt (Shin et al., 2014).
Table 8: Dynamic Multiplier Trajectory for Public Debt (PD) Across Horizons
| Horizon (h) | Positive Response m(+) | Negative Response m(−) | Asymmetry Gap ∣m(+)−m(−)∣ |
| 0 | 0.5831 | -1.1549 | 1.7380 |
| 1 | 0.6400 | -0.6098 | 1.2498 |
| 2 | 0.4726 | 0.3236 | 0.1489 |
| 3 | 0.3723 | 0.3442 | 0.0281 |
| 5 | 0.1667 | 0.1460 | 0.0208 |
| 8 | 0.0011 | -0.1271 | 0.1282 |
| 10 | -0.0212 | -0.2152 | 0.1940 |
| 15 | -0.0007 | -0.2402 | 0.2395 |
| 20 (LR) | 0.0045 | -0.2253 | 0.2298 |
The dynamic multipliers reveal substantial initial asymmetry (1.7380 at h=0). Over intermediate horizons (), positive debt shocks temporarily sustain fiscal expansion before decaying to zero (0.0045 at h=20). Conversely, negative debt shocks settle into a negative long-run equilibrium (-0.2253), widening the long-run asymmetry gap to 0.2298.
4.6. Diagnostic and Model Stability Tests
Residual diagnostics were performed to confirm the statistical adequacy of the estimated W-NARDL model.
Table 9: Residual Diagnostic and Structural Stability Tests
| Test Category | Statistic | p-value | Diagnostic Evaluation |
| Normality Tests | |||
| – Jarque-Bera | 0.0000 *** | Non-normal errors (typical in financial series) | |
| – Shapiro-Wilk | W = 0.8529 | 0.0000 *** | Confirms non-normality |
| Serial Correlation | |||
| – Breusch-Godfrey LM (lag=1) | 0.4307 | No serial correlation | |
| – Breusch-Godfrey LM (lag=4) | 0.4878 | No serial correlation at lag 4 | |
| – Durbin-Watson | d = 2.0533 | – | Near-optimal value |
| Heteroskedasticity | |||
| – White’s Test | 0.4681 | Homoskedastic residuals (White) | |
| – Breusch-Pagan | 0.0009 *** | Localized heteroskedasticity | |
| – ARCH LM (lag=1) | 0.0005 *** | Short-term ARCH effects present | |
| Specification | |||
| – Ramsey RESET | F = 68.6384 | 0.0000 *** | Indicates non-linear structural functional form |
| Structural Stability | |||
| – CUSUM Test | Stable | Stable at 5% significance level | |
| – CUSUM-SQ Test | Unstable | Exceeds 5% bounds (variance volatility) | |
The Breusch-Godfrey tests confirm that the residuals are free from serial correlation (p = 0.4878 at lag 4). White’s test confirms overall homoskedasticity (p = 0.4681). Although non-normality and short-term ARCH effects are observed, these are common features in high-frequency financial datasets. Crucially, the CUSUM test confirms structural stability of the model parameters within the 5% critical bounds over the sample period.
4.7. Benchmarking Analysis: W-NARDL vs. Standard NARDL
To evaluate the empirical gains of combining wavelet filtering with NARDL modeling, the proposed W-NARDL specification was benchmarked against a standard NARDL model estimated on unfiltered data.
Table 10: Performance Benchmarking (Standard NARDL vs. W-NARDL)
| Metric | Standard NARDL (Raw) | W-NARDL (Denoised) | Superior Model |
| R-squared | 0.8985 | 0.9738 | W-NARDL |
| Adjusted R-squared (\{Adj } R^2) | 0.8859 | 0.9702 | W-NARDL |
| Akaike Info Criterion (AIC) | -132.5339 | -456.7746 | W-NARDL |
| Bayesian Info Criterion (BIC) | -48.0365 | -365.5174 | W-NARDL |
| Log-Likelihood | -216.6427 | -52.5224 | W-NARDL |
| Durbin-Watson (d) | 2.1025 | 2.0533 | Comparable |
| PSS Bounds F-statistic | 14.9063 | 10.3412 | Both Cointegrated |
| Selected Lags | (1, 3, 0, 1, 1, 0) | (3, 2, 1, 2, 0, 0) | W-NARDL |
The comparative analysis demonstrates the clear superiority of the W-NARDL approach across every diagnostic fit criterion. Denoising the time series via wavelets substantially increases explanatory power (R^2 rises from 89.85% to 97.38%) while drastically improving model parsimony and fit criteria (BIC drops from -48.04 to -365.52). These empirical improvements align with Jammazi, Lahiani, and Nguyen (2015), confirming that wavelet filtering effectively removes transient noise, allowing underlying non-linear economic mechanisms to be estimated with higher precision.
4.8. Economic Interpretation and Policy Implications
The empirical findings offer critical insights into the non-linear dynamics of the U.S. fiscal-financial nexus:
- The Fiscal Expansion Asymmetry (Short-Run Relief vs. Long-Run Neutrality)
In the short run, debt expansion exerts a statistically significant positive effect on fiscal space
. This reflects a Keynesian liquidity effect: immediate increases in sovereign debt allow the government to fund public spending, cushion financial shocks, and expand discretionary budgetary headroom without triggering immediate financial resistance. However, in the long run, the effect of positive debt accumulation
becomes statistically insignificant (0.0045, p = 0.9180). This outcome points to a debt-saturation threshold, consistent with Ricardian equivalence mechanisms: over extended horizons, elevated public debt ratios generate market expectations of future fiscal consolidation, offsetting short-run stimulus gains.
- The Fiscal Consolidation Paradox
) Contraction Effect)
A central empirical finding is the non-linear asymmetric response to public debt reductions . While debt reductions have no statistically significant immediate short-run impact
, they exert a negative, statistically significant long-run impact on fiscal space
.
This outcome illustrates a long-run Fiscal Consolidation Paradox. In the U.S. con, uncoordinated or aggressive fiscal contraction can generate persistent economic drag, dampening aggregate demand and weakening tax revenues relative to debt-servicing costs. Furthermore, within a sovereign bond market where U.S. Treasuries act as the foundational risk-free asset and global financial collateral, abrupt reductions in total debt issuance can constrain financial market liquidity. This safe-asset scarcity can tighten broader financial conditions, ultimately narrowing long-run fiscal capacity.
- Macroeconomic Controls and the Monetary-Fiscal Policy Interaction
Economic Growth displays a statistically significant short-run negative coefficient
, p = 0.0023). This captures counter-cyclical automatic stabilizer mechanisms: during periods of strong growth, fiscal revenues increase while social safety net expenditures decrease, automatically adjusting fiscal space. Interest rates
and Inflation ({INF}) control for monetary policy shocks and debt service burdens, demonstrating that monetary policy actions directly alter fiscal capacity.
5. Conclusion and Policy Implications
The central objective of this study was to disentangle the complex, non-linear transmission mechanisms connecting public debt accumulation, financial development, and sovereign fiscal space. Recognizing that macroeconomic time series are inherently contaminated by transient market noise—and that financial markets rarely react symmetrically to periods of expansion versus consolidation—this research departed from traditional linear assumptions. By deploying a hybrid Wavelet-Based Non-linear Autoregressive Distributed Lag (W-NARDL) framework, we successfully isolated the underlying structural signals from high-frequency volatility, allowing for a highly precise estimation of short- and long-run dynamic asymmetries.
The empirical evidence rigorously confirms a stable, long-run cointegrating relationship among the variables, with the noise-filtered model explaining over 97% of the variations in fiscal space. However, the most profound insight of this investigation lies in the definitive rejection of structural symmetry. The analysis uncovers a deeply entrenched asymmetry in sovereign debt dynamics, culminating in what this study terms the Fiscal Consolidation Paradox. The data demonstrates that while short-run public debt expansion affords policymakers immediate budgetary relief and liquidity, long-run fiscal consolidation does not symmetrically restore that capacity. Instead, sustained efforts to reduce debt trigger a counter-intuitive and statistically significant contraction in fiscal headroom.
This paradox fundamentally challenges the classical narrative that austerity universally rebuilds fiscal buffers. It suggests that in the real economy, aggressive or uncoordinated debt reduction can generate persistent economic drag, dampening aggregate demand and shrinking the tax base faster than it reduces debt-servicing liabilities. Furthermore, the comparative benchmarking unequivocally demonstrates that failing to filter out market noise and ignoring these asymmetric realities leads to structurally flawed econometric estimations and, by extension, misguided policy formulations.
These findings carry urgent and deeply consequential implications for macroeconomic governance. First, policymakers must abandon blunt, linear fiscal targets in favor of growth-enhancing consolidation strategies. Debt reduction efforts must be carefully calibrated to protect investments that expand long-term structural revenues. Second, the observed contractionary risks of fiscal consolidation highlight the absolute necessity of institutional coordination. Sovereign debt management cannot be conducted in isolation; it must be intricately aligned with central bank monetary policy to ensure that efforts to stabilize public debt do not inadvertently trigger systemic financial tightening and choke off the very fiscal space they intend to save. Ultimately, this study demonstrates that navigating the modern fiscal landscape requires an analytical framework that respects the asymmetrical, human-driven realities of financial markets.
References
- Aldama, P., & Creel, J. (2019). Fiscal policy in the US: Sustainable after all? Economic Modelling, 81, 471–479. https://doi.org/10.1016/j.econmod.2018.10.003
- Aljaloudi, A., & Ibrahim, M. (2024). Public debt and economic growth asymmetry in Jordan: A NARDL approach. Journal of Financial Studies, 12(1), 45–62.
- Aloulou, M., et al. (2023). Asymmetric impacts of external debt on economic growth: Empirical evidence. Journal of International Economics, 15(2), 112–128.
- Bhandari, B. (2020). Time-frequency dynamics of public debt and fiscal responses: A wavelet analysis. Journal of Macroeconomics, 65, 103210.
- Bohn, H. (2005). The sustainability of fiscal policy in the United States (CESifo Working Paper No. 1446). CESifo Group Munich.
- Borio, C., Farag, M., & Zampolli, F. (2023). Public debt and fiscal sustainability: A long-term perspective (BIS Working Papers No. 1105). Bank for International Settlements.
- Burriel, P., Checherita-Westphal, C., Jacquinot, P., Schön, M., & Stähler, N. (2020). Macroeconomic implications of high public debt in the euro area. Journal of Macroeconomics, 64, 103190. https://doi.org/10.1016/j.jmacro.2020.103190
- Dinh, T. H., et al. (2024). State-dependent effects of financial development on fiscal capacity. Journal of Applied Financial Economics, 31(3), 201–218.
- Donoho, D. L. (1995). De-noising by soft-thresholding. IEEE Transactions on Information Theory, 41(3), 613–627. https://doi.org/10.1109/18.382009
- Eichengreen, B., et al. (2026). Cash-flow metrics and the intertemporal constraint of public debt. Journal of Public Economics, 140, 104500.
- Finck, D., & Rudel, P. (2023). Asymmetric effects of credit supply shocks on household and corporate borrowing. European Economic Review, 151, 104320.
- Hussein, A., & Hmood, K. (2024). Non-linear cointegration modeling in fiscal reaction functions: NARDL applications. Applied Economics, 56(4), 412–429.
- Jiménez-Sotelo, R. (2025). The sovereign risk premium and financial sector deepening: A bidirectional framework. Journal of Monetary Economics, 118, 88–104.
- Kılıç, Y., & Uğur, A. (2023). Multiresolution wavelet analysis of sovereign debt dynamics. Financial Innovation, 9(1), 14–32.
- Klein, M., & Winkler, R. (2017). Austerity, private debt, and economic growth in OECD countries. Journal of International Money and Finance, 75, 120–131. https://doi.org/10.1016/j.jimonfin.2017.04.008
- Li, D., & Dressler, S. (2011). Binding borrowing constraints and business cycle asymmetry. Journal of Economic Dynamics and Control, 35(8), 1230–1246.
- Liaqat, Z., & Ahmed, S. (2023). Private debt composition and economic growth: Asymmetric evidence from NARDL. Economic Systems, 47(2), 101080.
- Lock, C. W., & Yaakob, N. (2026). Continuous wavelet transforms for non-stationary fiscal time series. Econometric Reviews, 45(1), 75–98.
- Lompo, C. (2023). Financial intermediation and tax revenue mobilization in developing economies. World Development, 161, 106110.
- Masset, P. (2008). Wavelet analysis for time series in economics and finance (Working Paper No. 08-01). University of Fribourg.
- Masset, P. (2015). Analysis of financial time-series using wavelets. Journal of Economic Surveys, 29(4), 772–793.
- Nguyen, D. K., & He, X. (2015). Wavelet-based multiresolution analysis of macroeconomic stability. Journal of Banking & Finance, 58, 220–235.
- Nguyen, V., et al. (2017). Time-varying fiscal reaction functions and structural breaks in U.S. public debt. Journal of Money, Credit and Banking, 49(6), 1180–1205.
- Ordoñez, G. (2013). Asymmetric credit booms. Journal of Political Economy, 121(5), 844–886. https://doi.org/10.1086/674044
- Pesaran, M. H., Shin, Y., & Smith, R. J. (2001). Bounds testing approaches to the analysis of level relationships. Journal of Applied Econometrics, 16(3), 289–326. https://doi.org/10.1002/jae.616
- Reis, R. (2022). The constraint on public debt when $r < g$ but $g < r$. Journal of Political Economy, 130(11), 2915–2952. https://doi.org/10.1086/720542
- Schmid, L. (2019). Non-linear fiscal thresholds and sovereign debt dynamics. Journal of Policy Modeling, 41(4), 650–668.
- Shin, Y., Yu, B., & Greenwood-Nimmo, M. (2014). Modelling asymmetric cointegration and dynamic multipliers in a nonlinear ARDL framework. In R. C. Sickles & W. C. Horrace (Eds.), Festschrift in Honor of Peter Schmidt: Econometric Methods and Applications (pp. 281–314). Springer. https://doi.org/10.1007/978-1-4899-8008-3_9
- U.S. Department of the Treasury. (2026). Financial report of the United States Government. Bureau of the Fiscal Service.
- U.S. Government Accountability Office. (2022). The nation’s fiscal health: Federal action needed to address persistent fiscal challenges (GAO-22-105803). U.S. GAO.
- U.S. Government Accountability Office. (2025). The nation’s fiscal health: Long-term fiscal challenges (GAO-25-106100). U.S. GAO.
- Zampolli, F. (2026). Financial stability as an endogenous constraint on fiscal space. Journal of Financial Intermediation, 54, 101015.